Bothell Multi Unit Insurance: Coverage Designed for Multi‑Unit Properties
Owning multiple rental units in Bothell comes with unique insurance challenges that standard homeowners policies simply don’t address. Your investment requires protection that accounts for multiple tenants, shared structures, and rental income-all of which demand specialized coverage.
We at First Rate Insurance Plus, Inc. help Bothell multi-unit property owners find policies that match their specific needs. This guide walks you through your coverage options and shows why the right insurance matters for protecting your bottom line.
What Multi-Unit Property Insurance Covers
Multi-unit property insurance protects buildings with two or more residential units under a single policy, covering the structure, liability exposure, and rental income that come with managing multiple households. Unlike a standard homeowners policy that covers only your primary residence, multi-unit coverage addresses the complexity of shared common areas, multiple tenants, and the business aspect of rental properties. A duplex, triplex, fourplex, or small apartment building all fall under this category. The key distinction is that these properties generate rental income, which creates different insurance needs than owner-occupied homes. Standard homeowners policies explicitly exclude rental units or limit coverage to one additional unit, leaving you dangerously underprotected if you own a true multi-unit investment.
Why Multi-Unit Properties Need Specialized Coverage
Bothell property owners with two or more rental units face significantly higher liability exposure than single-family homeowners. When multiple families live in one building, the risk of slip-and-fall incidents, injuries in common areas, or property damage multiplies.
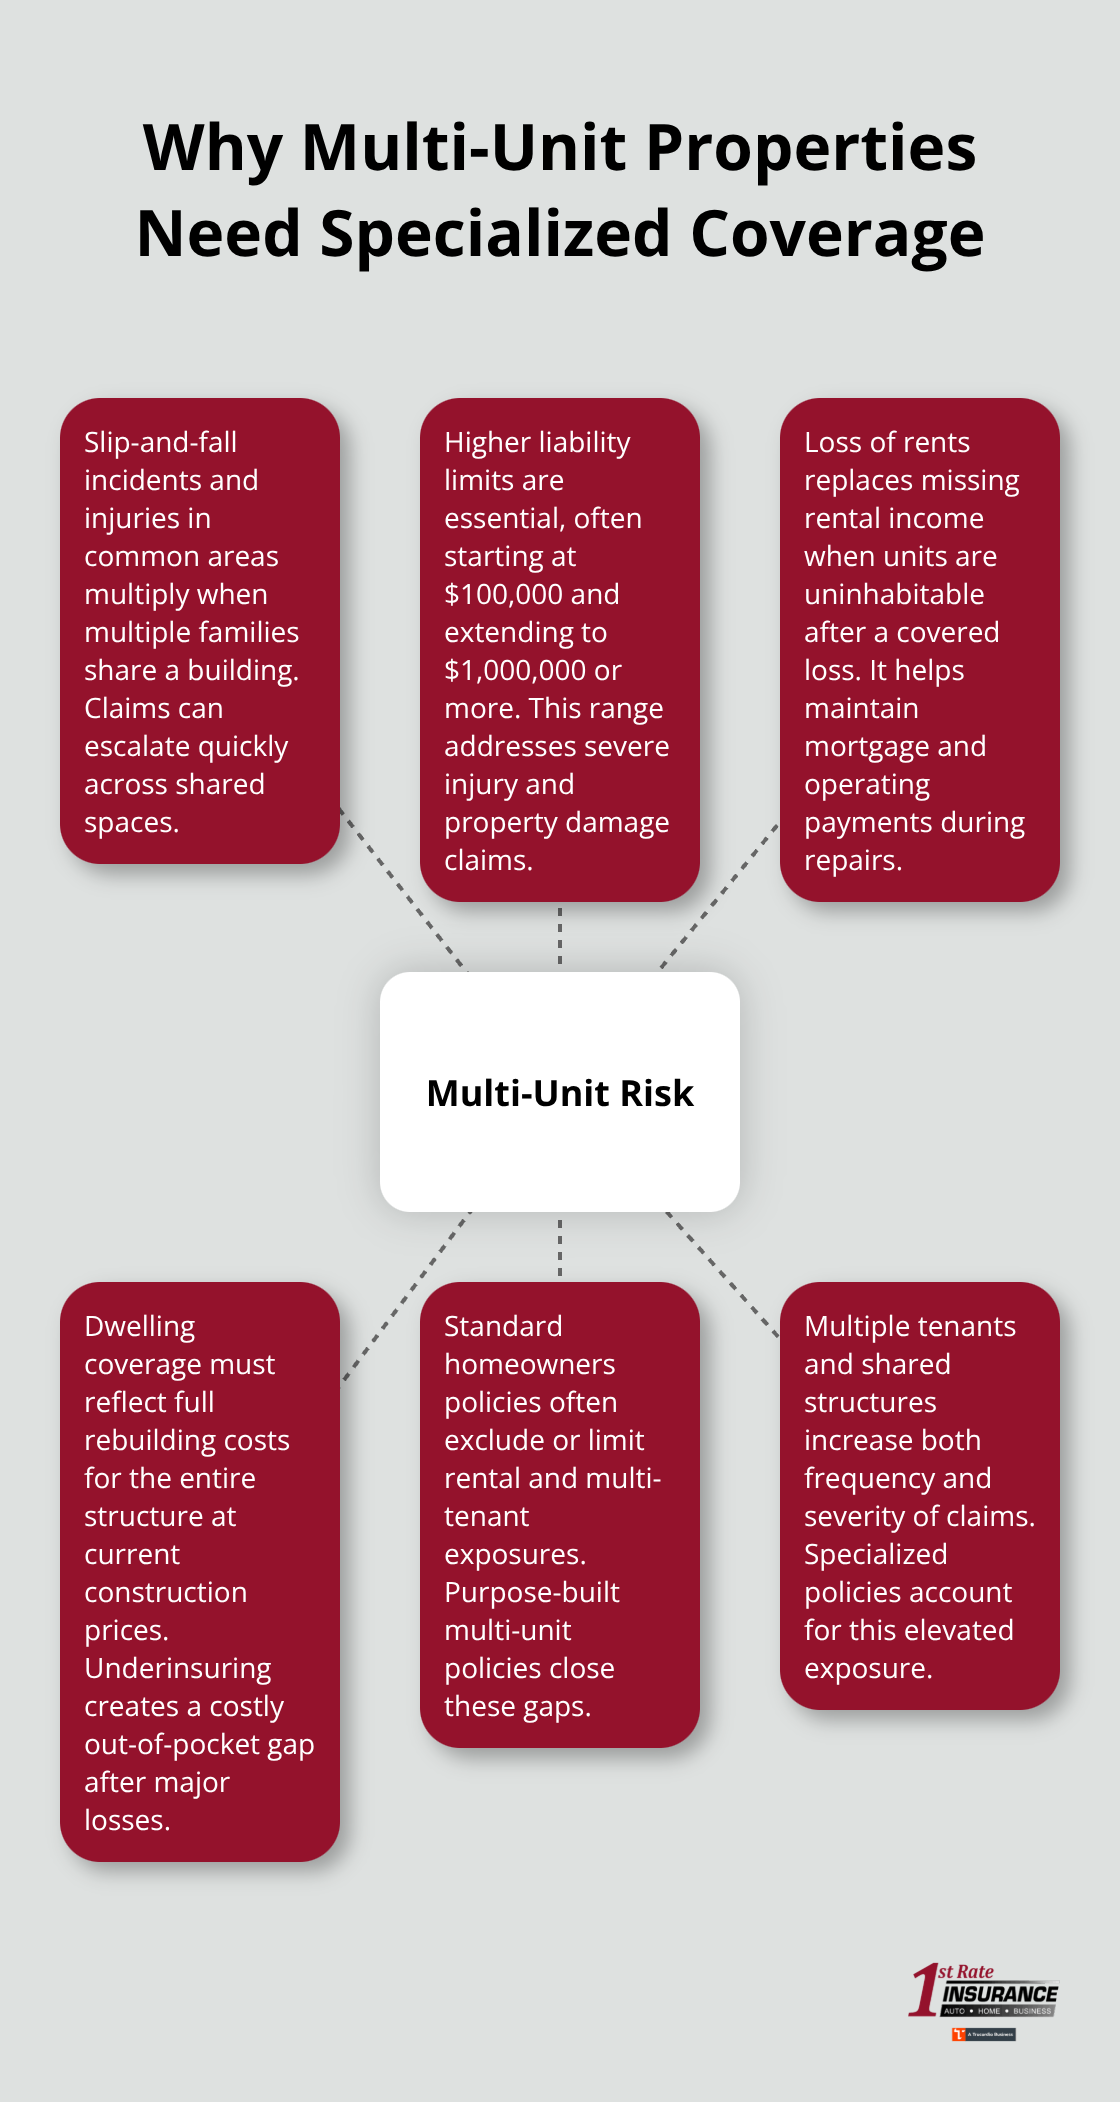
A tenant slips on icy stairs in February and files a serious lawsuit-your homeowners policy won’t cover it. Multi-unit policies account for elevated risk with liability limits that start at $100,000 and extend to $1,000,000 or more.
Additionally, when a tenant moves out or a unit becomes unlivable due to damage, you lose rental income while still carrying mortgage payments and maintenance costs. Standard policies don’t reimburse lost rent, but multi-unit policies do, protecting your cash flow during vacancy or repairs. The dwelling protection component also differs significantly-it covers the entire building structure and all units as an investment asset rather than a personal residence, which affects how replacement cost and depreciation are calculated.
The Coverage Gap in Standard Homeowners Policies
Most homeowners policies sold in Washington state explicitly exclude rental income coverage or limit it to situations where you rent out one accessory unit, according to guidelines from the National Association of Insurance Commissioners. If you own a duplex or triplex, your standard homeowners policy likely provides zero protection for rental income loss. Many agents fail to explain this gap until a claim happens.
Additionally, standard policies cap liability coverage at levels insufficient for multi-unit properties where multiple tenants could be injured or where property damage claims accumulate across units. You also won’t find coverage for loss assessment liability, which protects you if your HOA charges owners for shared losses-relevant if your multi-unit building has common ownership structures (such as condominiums or shared-expense arrangements). Multi-unit policies solve these problems with appropriate liability limits, actual loss of rents coverage, and provisions designed specifically for investment properties generating ongoing tenant income.
Finding the Right Coverage for Your Bothell Property
The specific coverage options you need depend on your property type, number of units, and tenant situation. We at First Rate Insurance Plus, Inc. work with property owners to identify which coverage components matter most for their investment. The next section breaks down the specific coverage options available and how they protect different aspects of your multi-unit property.
Coverage Options for Multi-Unit Properties
Dwelling Protection That Matches Your Investment
Dwelling coverage for multi-unit properties works differently than it does for single-family homes, and this distinction matters significantly for your bottom line. Your policy must cover the full rebuilding expense of the entire building at current construction costs, not the land value. In Washington, construction costs average $150 to $250 per square foot depending on building age and materials, according to recent RSMeans data. A four-unit building with 8,000 square feet could cost $1.2 million to $2 million to rebuild, yet many owners carry policies with $600,000 dwelling coverage. This gap leaves you personally liable for the shortfall.
Inflation adjusts replacement cost annually, but you need to review your coverage limits every two years because construction costs in the Puget Sound region have increased over the past year. The dwelling component also covers permanent structures like garages, storage buildings, and exterior improvements that add value to your investment property. Underestimating replacement costs creates serious financial exposure that most property owners don’t realize until a major loss occurs.
Liability Coverage for Multiple Units
Liability coverage separates responsible multi-unit owners from those gambling with their assets. A single serious injury claim in a common area can exceed $500,000 in medical expenses and legal fees within months. Standard homeowners policies max out at $100,000 to $300,000 liability protection, which disappears instantly in a major incident. Multi-unit policies typically start at $300,000 and extend to $1,000,000 or higher, covering bodily injury and property damage across all units simultaneously.
When multiple families occupy one building, slip-and-fall incidents, injuries in common areas, and property damage claims multiply your exposure. Your liability limits must reflect this elevated risk. Policies designed for multi-unit properties account for the complexity of shared spaces and multiple tenant households in ways that standard homeowners coverage simply cannot.
Loss of Rents and Additional Living Expenses
Loss of rents protection reimburses your rental income when units become uninhabitable due to covered damage, fire, or weather events. If a kitchen fire damages one unit and forces that tenant out for three months, loss of rents coverage replaces the missing $3,000 monthly income. Without this coverage, you still owe the mortgage while collecting nothing.
Additional living expenses coverage protects you if you must temporarily house a displaced tenant or cover their relocation costs as part of your lease obligations. These two components work together to protect both your property asset and your cash flow, which is what actually keeps multi-unit ownership viable. When damage strikes, this coverage prevents your investment from becoming a financial drain during the repair period.
Choosing the Right Coverage Limits
The specific coverage options you need depend on your property type, number of units, and tenant situation. Licensed agents who work with multiple carriers can help you identify which coverage components matter most for your investment. The next section explains why selecting the right insurance partner makes all the difference in protecting your Bothell property.
Why Multi-Unit Property Owners Need the Right Insurance Partner
Compare Prices Across Multiple Carriers
Shopping for multi-unit insurance in Bothell means comparing policies across multiple carriers to find the right balance between coverage and cost. Most property owners call one or two agents and accept whatever quote arrives first, which typically leaves them either overinsured and overpaying or underinsured and exposed. The insurance marketplace for investment properties varies dramatically between carriers-one company might charge $2,400 annually for a four-unit building while another charges $3,800 for identical coverage. This 58% price difference exists because carriers use different underwriting criteria, rate structures, and risk assessment models.
Shopping across multiple carriers isn’t optional if you want competitive pricing. It’s essential to understanding what your property actually costs to insure. We at First Rate Insurance Plus, Inc. shop more than 20 carriers, which means we can show you the actual price range available rather than guessing based on a single quote.
Customize Policies to Your Specific Property
Multi-unit properties require policies customized to your specific building layout, tenant turnover patterns, and local Bothell risk factors. A duplex where you occupy one unit needs different coverage than a four-unit building with four separate tenants. Properties near flood zones need different protection than buildings on higher ground. Older buildings with wood frame construction carry different liability exposure than newer concrete structures.
Agents who specialize in multi-unit coverage understand these distinctions and adjust policy recommendations accordingly. They recognize which coverage gaps matter most for your investment and which optional endorsements actually protect your bottom line versus which ones waste money.
Leverage Local Expertise and Market Knowledge
Local expertise matters significantly because agents familiar with Bothell’s building codes, weather patterns, and typical claim history identify coverage gaps that generic online quotes miss. An agent who handles multi-unit properties across Washington recognizes which carriers respond fastest to claims, which ones deny coverage for preventable maintenance issues, and which ones actually stand behind their policies when major losses occur.
Award-winning service means your agent answers calls within hours (not days) and handles claims with urgency rather than bureaucratic delays. This responsiveness becomes critical when damage strikes your building and you need immediate answers about coverage, claim procedures, and next steps.
Final Thoughts
Adequate dwelling coverage prevents you from absorbing reconstruction costs that exceed your policy limits, liability protection shields your assets from tenant injuries and property damage claims, and loss of rents coverage keeps your cash flow intact when units become uninhabitable. Construction expenses, liability exposure, and rental income loss all factor into determining appropriate coverage limits for your Bothell multi unit insurance. Most property owners underestimate at least one of these components, which creates dangerous gaps that emerge only when claims happen.
Shopping across multiple carriers reveals the actual price range available for your specific building, tenant situation, and risk profile. Local agents who understand Bothell’s building codes, weather patterns, and claim history identify coverage gaps that generic online quotes miss. This expertise matters most when damage strikes your building and you need answers about coverage and claim procedures.
Contact First Rate Insurance Plus, Inc. to get a quote on multi-unit coverage tailored to your Bothell property. Our licensed agents will review your building details, compare options across carriers, and show you exactly what your investment costs to protect properly.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.