Home Insurance Discounts Washington: Save On Your Policy
Washington homeowners often overpay for coverage without realizing how many discounts they qualify for. At First Rate Insurance Plus, Inc., we’ve seen customers cut their premiums by hundreds of dollars annually simply by understanding what savings are available.
Home insurance discounts in Washington range from bundling policies to rewarding safety upgrades and claim-free years. The key is knowing which discounts apply to your situation and how to stack them for maximum savings.
Which Washington Home Insurance Discounts Actually Save You Money
Bundling policies delivers the biggest immediate savings
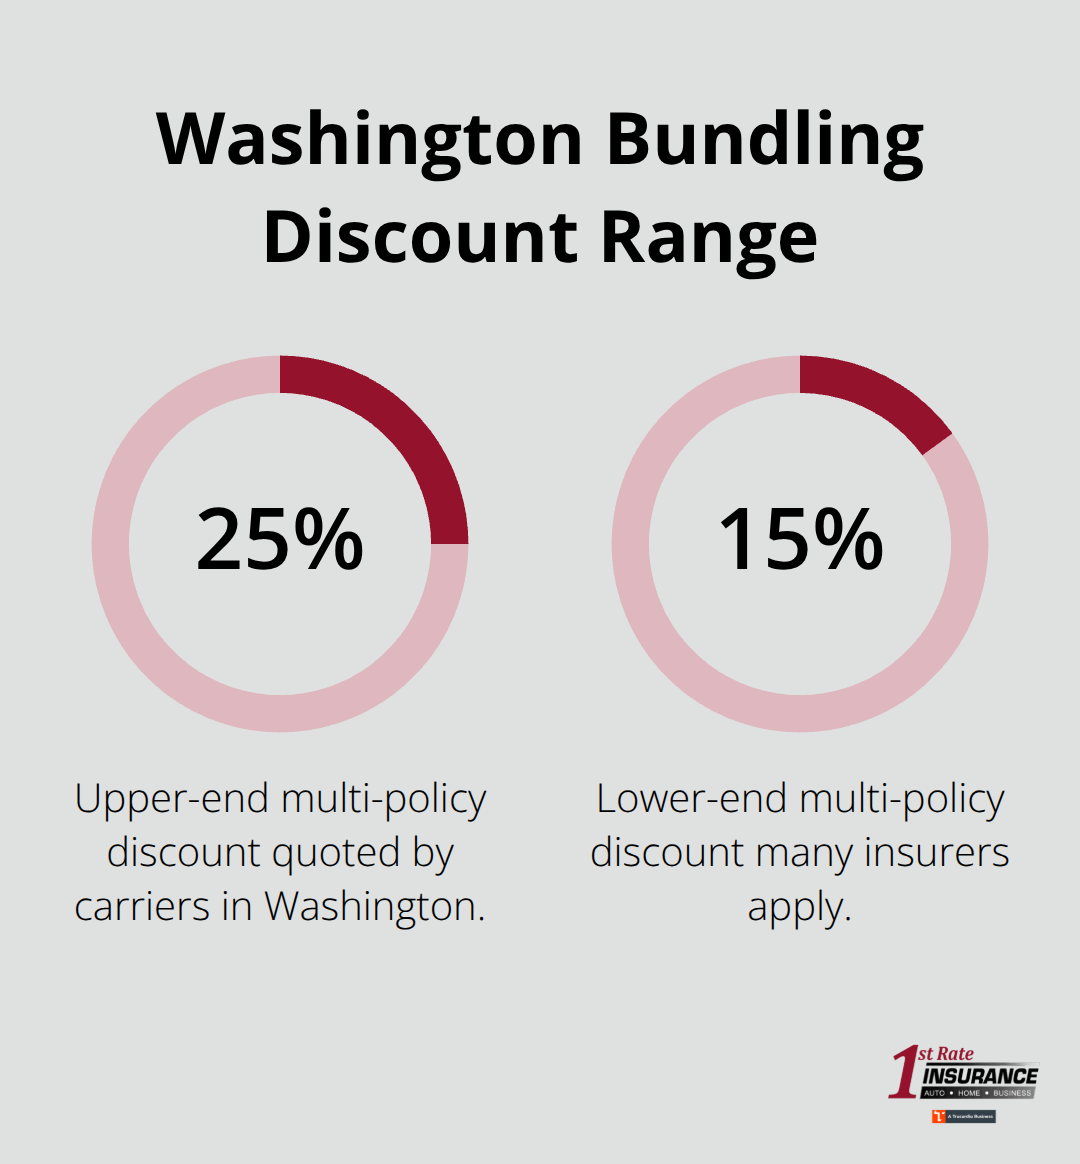
Bundling your home and auto policies remains the single most effective way to reduce your insurance costs in Washington. Liberty Mutual reports that customers bundling auto and home save over $950 annually, while other carriers offer similar multi-policy discounts that can reduce your total premium by 15 to 25 percent. Insurers reward loyalty across multiple lines of coverage, and you benefit from lower rates on both policies. This isn’t a marginal savings-it’s substantial money that stays in your pocket. If you currently split your home and auto insurance between different carriers, you likely leave hundreds of dollars on the table each year.
Safety upgrades recover their cost within one to two years
Washington homeowners who install protective devices-deadbolt locks, smoke alarms, fire extinguishers, or security systems-qualify for immediate premium reductions. Farmers Washington specifically offers a Protective Devices discount for eligible safety features, and many carriers in the state follow similar models. These upgrades typically cost between $200 and $800 installed, yet your discount can recover that investment within one to two years. A security system that costs $500 to install might reduce your annual premium by $300 to $400, meaning you break even quickly while also gaining the actual safety benefit. Non-smoker discounts also apply in Washington, providing additional savings for households without tobacco use. You shouldn’t view these safety investments as pure expenses-they’re investments that pay dividends through lower premiums while simultaneously protecting your home.
Claims history and loyalty unlock long-term savings
Insurers reward customers who maintain claim-free records, and in Washington’s competitive market, this loyalty discount can range from 5 to 15 percent depending on your carrier and how many years you’ve remained claim-free. However, the opposite is equally true: a single claim can increase your rates by 10 to 40 percent for three to five years. Filing a claim for minor damage sometimes costs more in premium increases than simply paying out of pocket. You need to calculate whether your deductible makes the claim worthwhile or whether absorbing the cost preserves your long-term savings. Additionally, staying with the same insurer for multiple years unlocks loyalty rewards that new customers don’t receive, making a carrier switch a decision that should account for the value you’ve already built through your claims-free history.
The next step: qualifying for these discounts requires action
Understanding which discounts exist is only half the battle. The carriers that reward safety upgrades, bundling, and loyalty won’t automatically apply these savings to your policy-you must actively qualify for them and confirm your eligibility with your agent.
How to Qualify for Washington Home Insurance Discounts
Install security features and document everything
Qualifying for discounts requires concrete steps that insurers can verify. Start with your home security systems, because this is where you gain immediate, measurable savings. If your home lacks a security system, deadbolt locks, or smoke alarms, installing these features qualifies you for discounts that typically range from 5 to 15 percent on your annual premium. A basic security system monitored by a professional company costs between $300 and $600 installed, and many insurers like Farmers Washington will reduce your premium by $300 to $500 annually through their Protective Devices discount. Your investment recovers within one year while you simultaneously gain actual protection.
Verify with your insurer before purchasing any system, because some carriers require professional monitoring while others accept self-monitored systems. Once installed, document the system with photos and receipts, then provide this documentation to your agent so the discount applies immediately to your next renewal. Insurers won’t apply the discount without proof-this step separates customers who save from those who don’t.
Protect your claims-free status at all costs
Your claims history determines whether discounts stick around or disappear entirely. Maintaining a claim-free record for three to five years qualifies you for loyalty discounts that can reduce your premium by 5 to 15 percent, but filing even one claim can erase those accumulated savings and increase rates by 10 to 40 percent for years afterward. The math here is brutal: a $500 claim might cost you $1,500 to $2,000 in premium increases over the next three to five years.
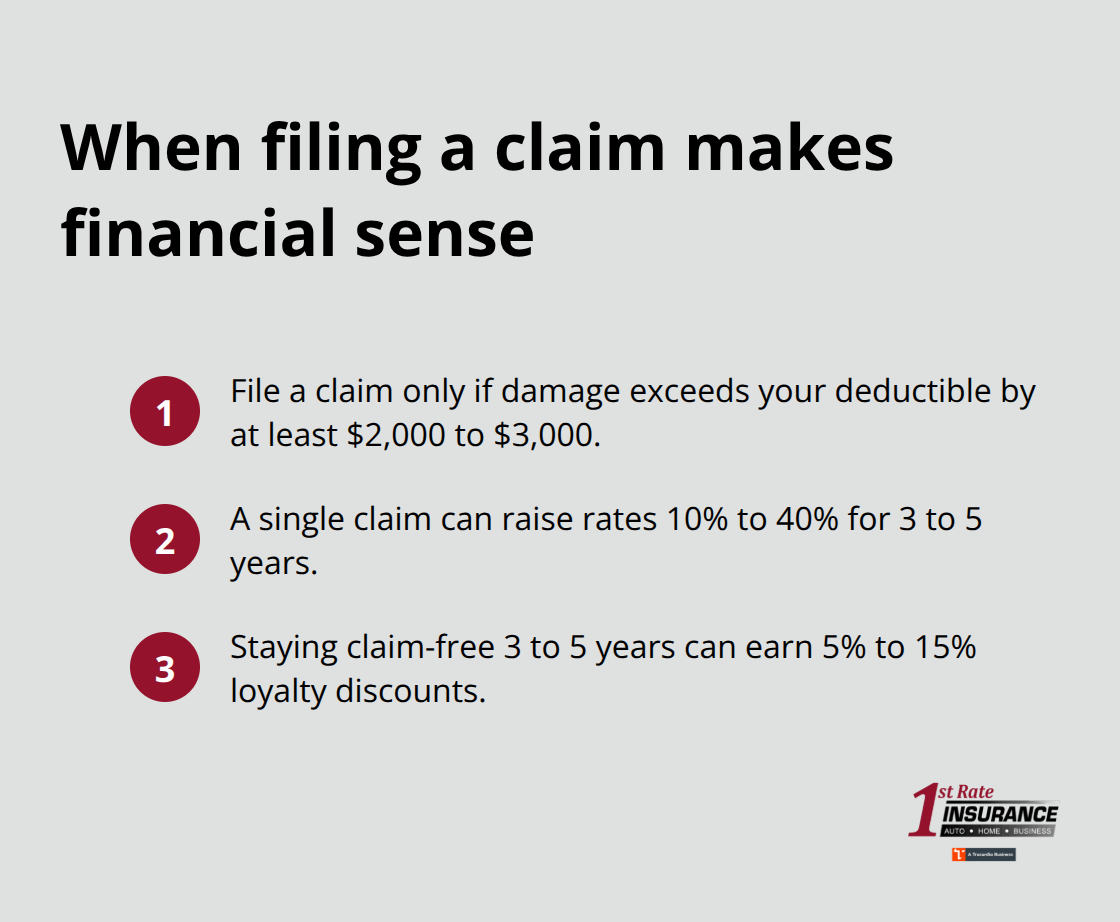
File claims only when the damage exceeds your deductible by a significant margin-typically at least $2,000 to $3,000. For minor damage, paying out of pocket preserves your claims-free status and protects your long-term savings. This strategy requires discipline, but the long-term financial benefit far outweighs the short-term convenience of filing a claim.
Compare quotes from at least three carriers
Discount eligibility varies dramatically between insurers. One carrier might offer a 20 percent bundling discount while another offers 10 percent, and some carriers provide discounts for new home construction or recent renovations that others don’t recognize at all. Get quotes from at least three carriers in Washington before renewing, because switching to a carrier with better discounts can save you $300 to $600 annually, and that advantage compounds every year you remain with that carrier.
The discount landscape shifts constantly as carriers adjust their programs and introduce new incentives. What saves you money with one insurer might not apply with another, which means your renewal decision should factor in the total discount package available, not just the base rate. This comparison process takes time, but the financial payoff justifies the effort-especially when you discover that a carrier you’ve never considered offers substantially better savings for your specific situation.
Maximizing Your Savings on Home Insurance in Washington
Stack multiple discounts for dramatic savings
Most Washington homeowners leave money on the table because they qualify for multiple discounts but never combine them effectively. A single discount saves you 5 to 15 percent, but stacking three or four discounts compounds the savings dramatically. Combine bundling with other available discounts for maximum savings, as insurance companies offer numerous discount programs that stack with multi-policy savings. On a $1,225 baseline annual cost for Washington homeowners insurance according to NerdWallet data, that difference amounts to $430 annually. Insurers structure their discounts to reward customers who take multiple qualifying actions, yet they won’t automatically layer these savings without your direct request.
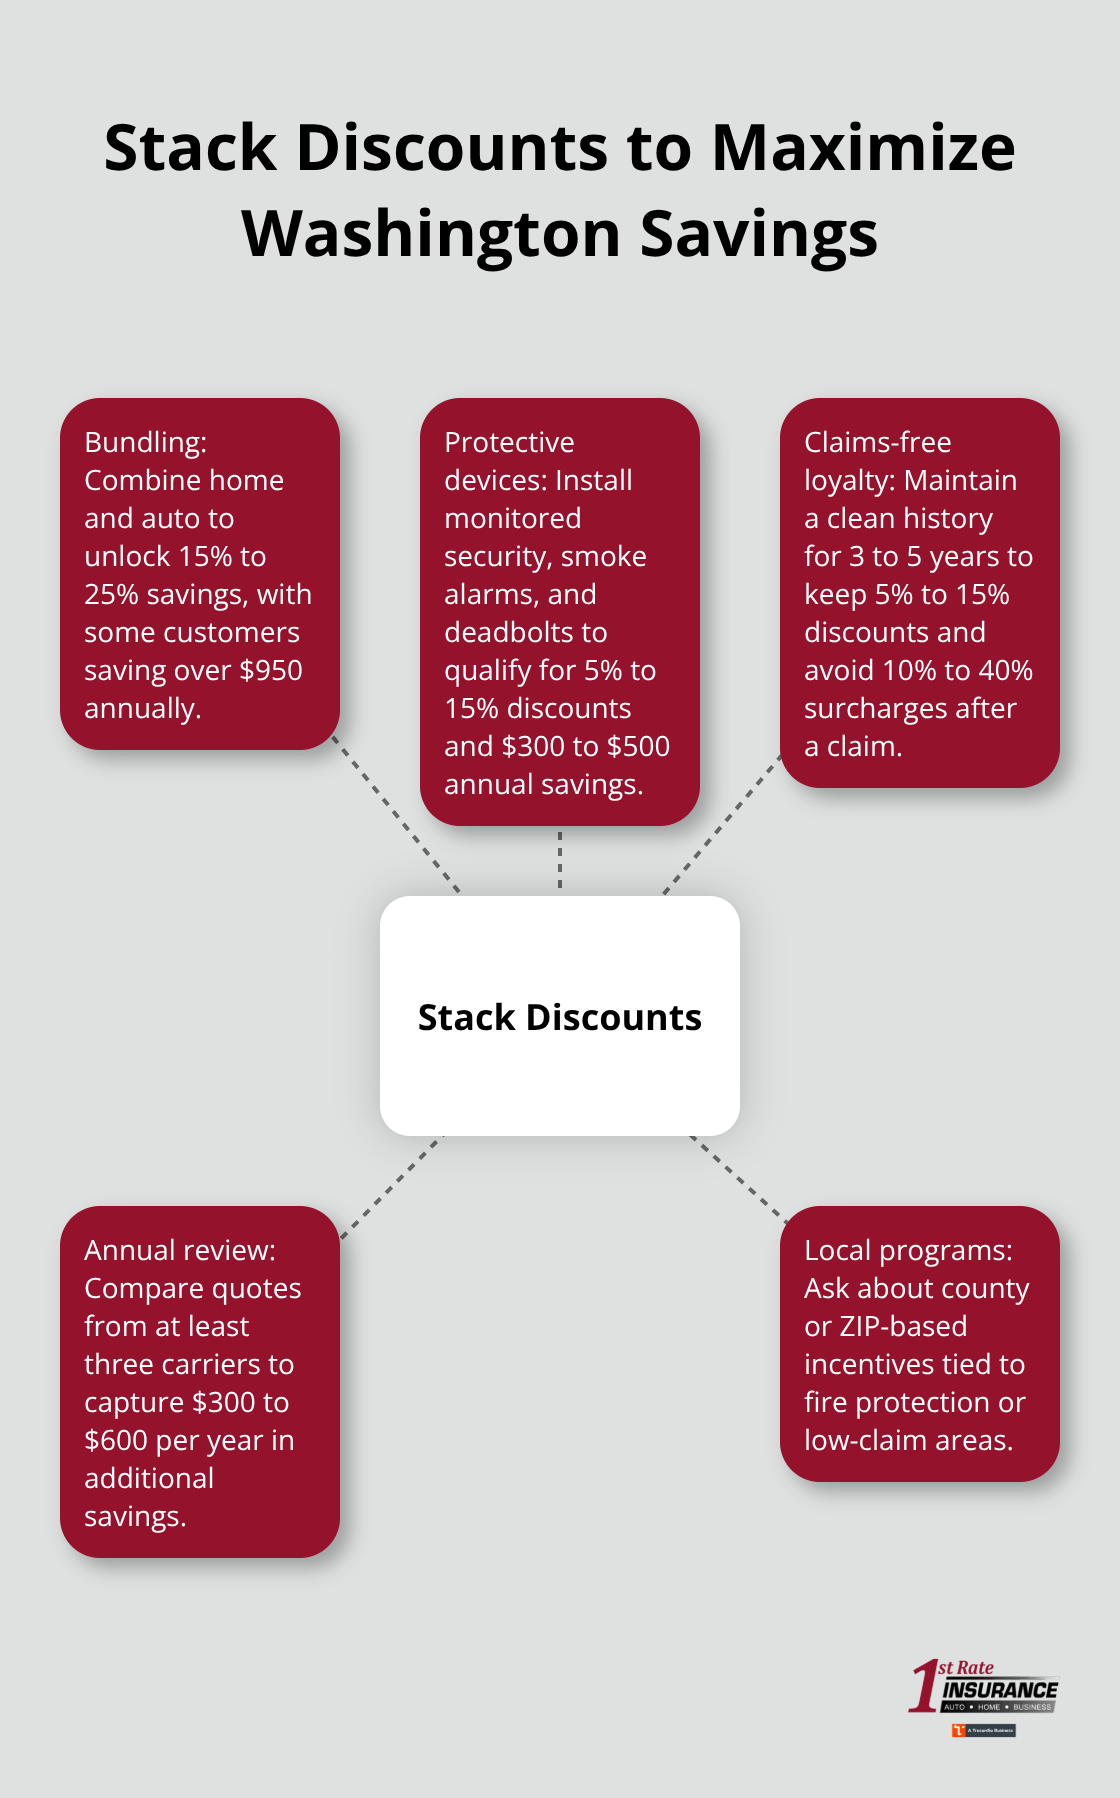
Contact your agent and explicitly ask which discounts apply to your situation, then confirm each one appears on your renewal quote. Document everything-your security system installation, your bundled policies, your claims-free years-because this documentation forces your insurer to apply every discount you’ve earned. Many customers accept their renewal quote without questioning whether all eligible discounts appear, and this passivity costs hundreds annually.
Revisit your policy annually to capture new opportunities
Your policy changes every year as your home ages, your coverage needs shift, and new discounts emerge in the market. Review your coverage each renewal and ask your agent about discounts you didn’t qualify for previously, because life circumstances change. A recent home renovation might unlock a new construction discount, aging out of a rental property could eliminate certain coverage requirements, or a security system installation finally qualifies you for that protective devices discount you skipped before.
Regional and local discount programs vary by county and city within Washington, meaning your neighbor’s available discounts might differ from yours. When you shop quotes from multiple carriers, specifically ask about local programs and regional incentives tied to your zip code, because some insurers offer discounts for areas with excellent fire protection or low-claim histories. The effort to explore these options during renewal takes two to three hours, yet the financial payoff typically reaches $300 to $600 annually compared to your previous renewal rate.
Final Thoughts
Washington homeowners who act on these strategies typically reduce their annual premiums by $400 to $800 through home insurance discounts in Washington. Bundling policies delivers the largest immediate savings, safety upgrades pay for themselves within two years, and maintaining a claims-free record compounds your discounts over time. The combination of these three approaches-bundling, security investments, and disciplined claims management-creates substantial long-term savings that most homeowners never capture.
Your next steps are straightforward: obtain quotes from at least three carriers and compare their bundling discounts, protective device discounts, and loyalty programs. Install security features if your home lacks them, document everything with photos and receipts, and confirm your agent applies the discount to your renewal. Protect your claims-free status by filing claims only when damage significantly exceeds your deductible. Review your policy annually and ask about new discounts tied to home renovations, regional programs, or life changes that might qualify you for additional savings.
A local insurance agent makes this process dramatically simpler by shopping multiple carriers simultaneously and identifying which discounts apply to your specific situation. Contact First Rate Insurance Plus, Inc. at https://1strateins.com/ to discuss your home insurance options and discover how much you can save through the right combination of discounts and coverage.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.