Kirkland Homeowners Discounts WA: Save On Home Insurance
Kirkland homeowners have more ways to cut insurance costs than most realize. At First Rate Insurance Plus, Inc., we’ve helped countless Washington residents find discounts they didn’t know existed.
The difference between paying full price and getting real savings often comes down to knowing what to ask for. This guide shows you exactly where those savings hide.
What Discounts Actually Work for Kirkland Homeowners
Bundle Auto and Home Policies for Maximum Savings
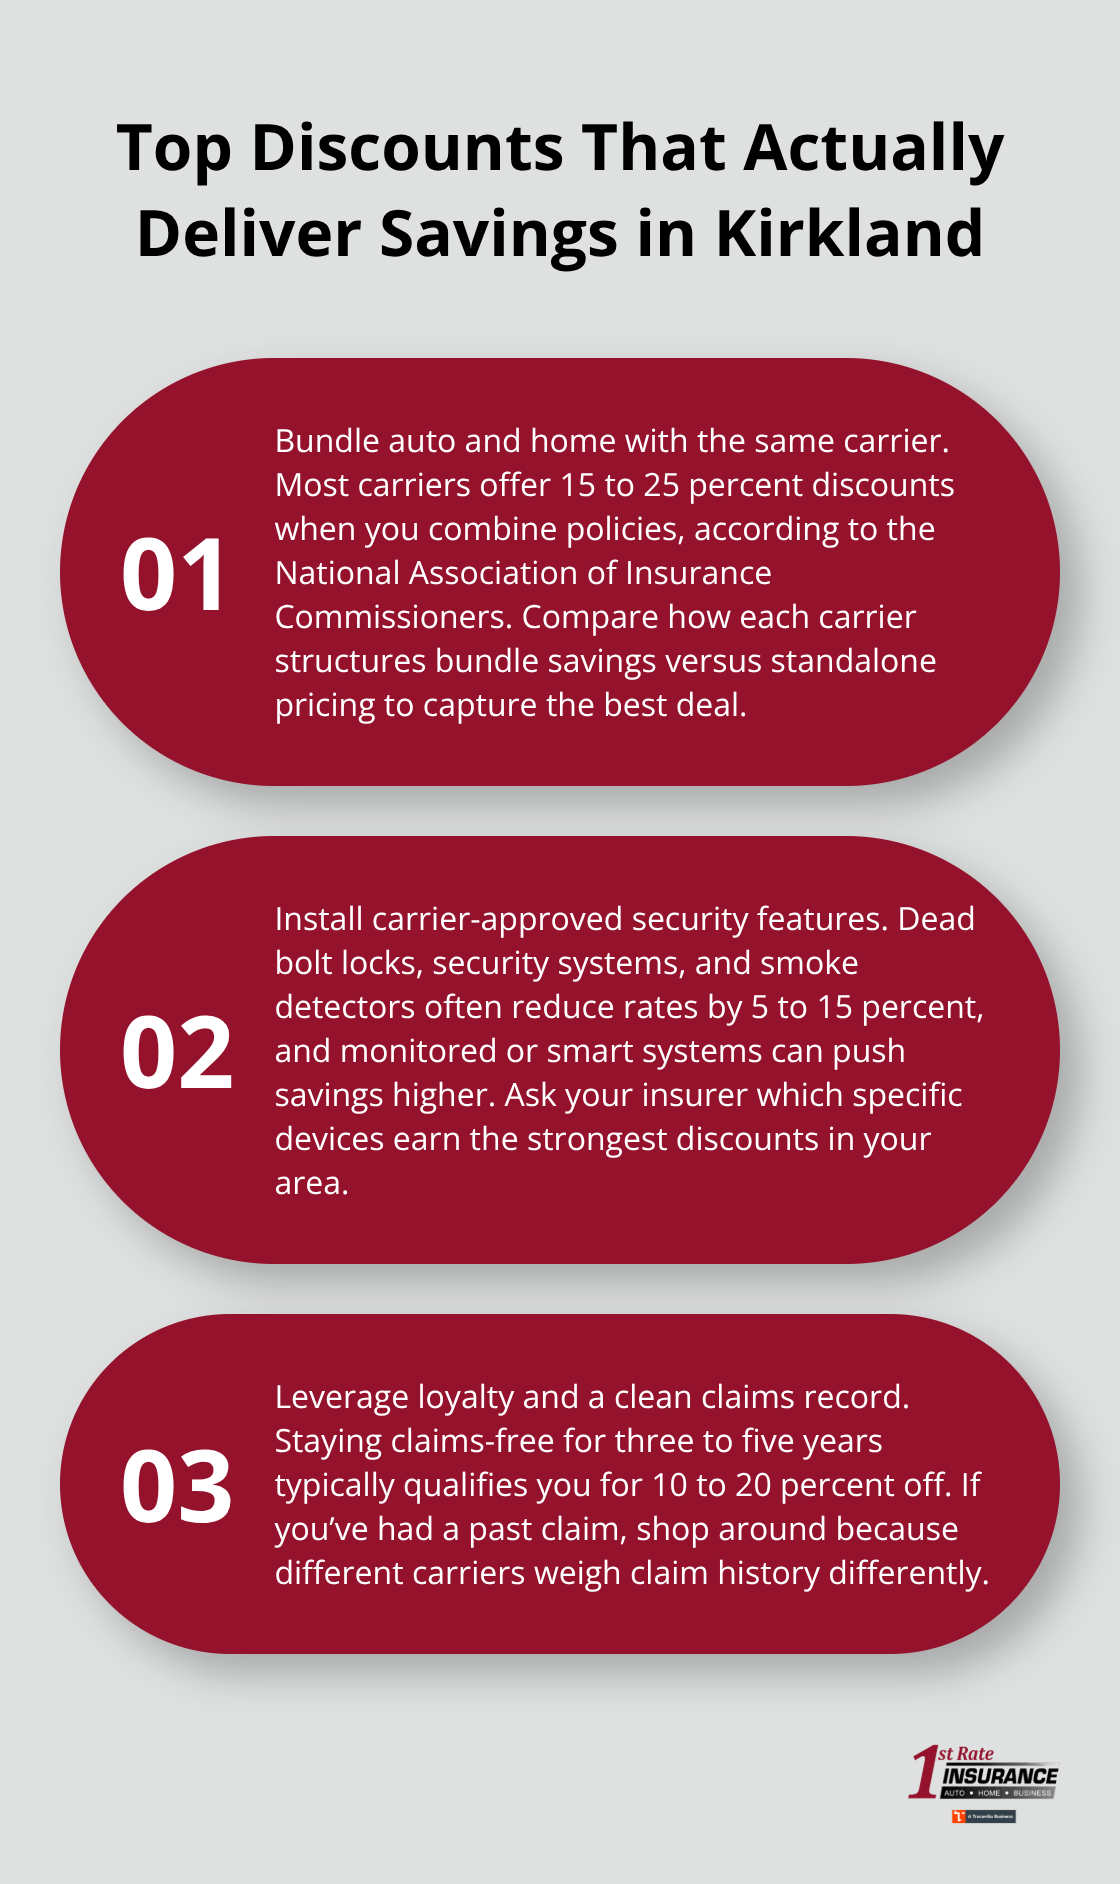
Bundling your auto and home policies remains one of the fastest ways to cut your insurance bill. Most carriers offer 15 to 25 percent discounts when you combine policies, according to the National Association of Insurance Commissioners. First Rate Insurance Plus, Inc. shops more than 20 carriers, which means we can match you with companies that offer the strongest bundling incentives for your specific situation. The real savings happen when you compare what each carrier bundles versus what they charge separately. Some companies discount auto heavily but keep home rates high, while others do the opposite. That’s why shopping across multiple carriers matters far more than accepting the first bundle offer you receive.
Security Features That Carriers Actually Reward
Kirkland homeowners often overlook how much security upgrades lower premiums. Dead bolt locks, security systems, and smoke detectors reduce your rate by 5 to 15 percent with most insurers. More advanced systems like monitored alarm services or smart home security cameras push discounts even higher. The Insurance Information Institute reports that homes with security systems file fewer claims, which is exactly why carriers incentivize them. Before upgrading, contact your insurer to ask which specific features they reward most generously in your area. A 500 dollar security system investment that saves you 30 dollars monthly pays for itself in less than two years and continues saving you money long after. Earthquake-resistant bracing and updated electrical systems also qualify for discounts in Washington, particularly in Kirkland where seismic activity remains a consideration.
Loyalty and Claims History Drive Real Savings
Your track record as a customer matters significantly more than most homeowners realize. Staying claims-free for three to five years typically qualifies you for loyalty discounts ranging from 10 to 20 percent. Insurers reward customers who avoid filing claims because statistically those customers cost them less money. If you’ve been with the same carrier for multiple years without claims, you’re sitting on thousands of dollars in potential savings that you may never access unless you ask directly. The opposite also holds true: if you filed a claim five years ago, that incident likely still impacts your rates today, which means shopping around becomes essential. Different carriers weight past claims differently, so moving your policy to a company that views your history more favorably can produce substantial savings. Annual policy reviews give you the chance to reassess your claims history and ask whether your current rate reflects your actual risk profile.
Now that you understand which discounts work best, the next step involves comparing quotes across multiple carriers to see how these discounts actually apply to your specific home and situation.
How to Shop Around and Find Your Best Rate
Compare Quotes Across Multiple Carriers
The same house with identical coverage costs 40 to 60 percent more at one carrier than another, according to the National Association of Insurance Commissioners. Most Kirkland homeowners never discover this variation because they stop after requesting two quotes and assume they’ve completed their research. That approach leaves thousands of dollars on the table.
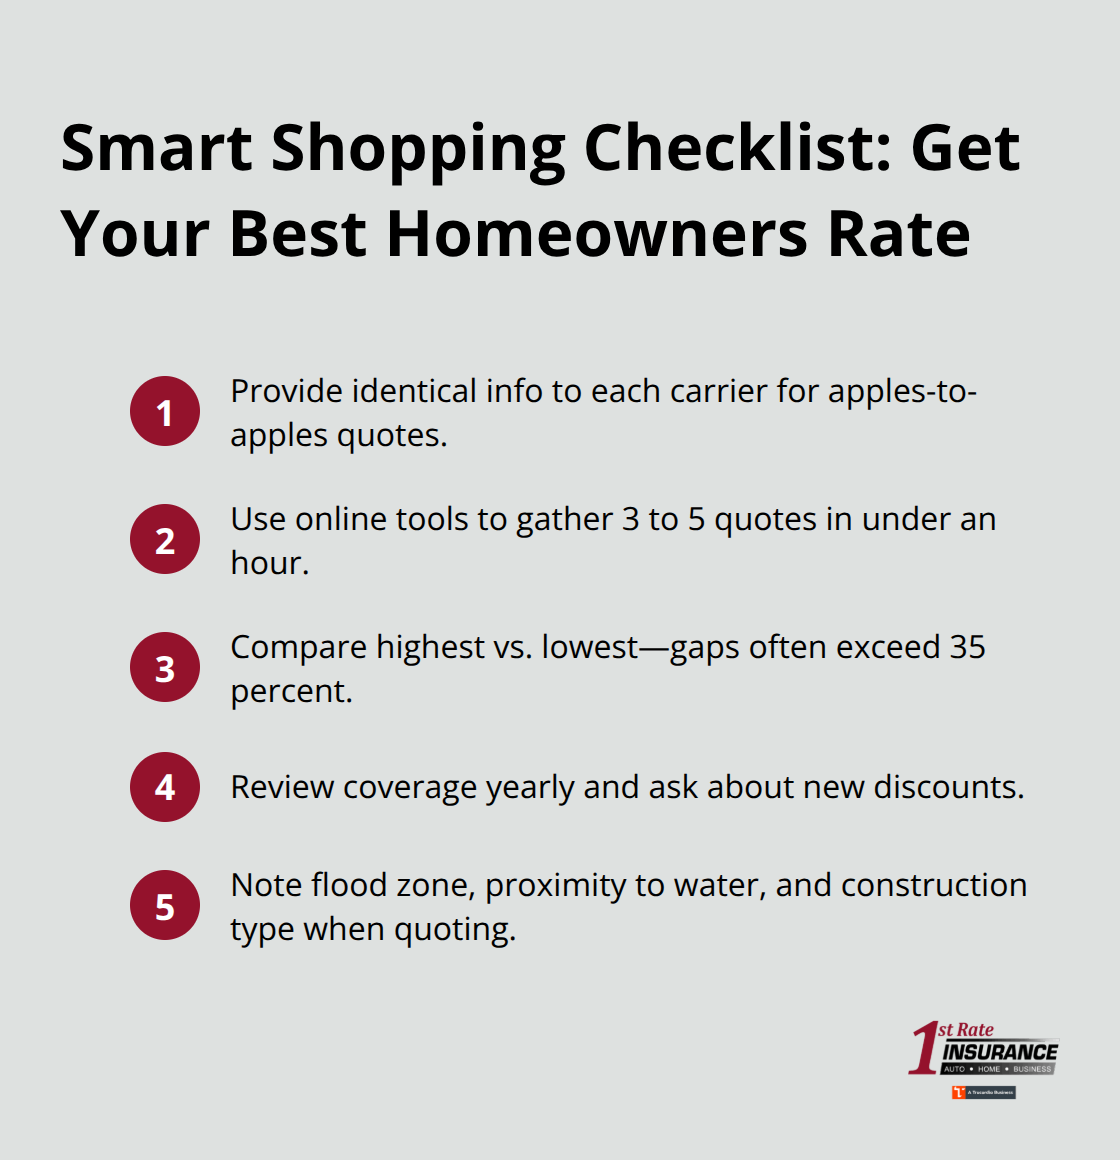
When you request quotes, provide identical information to each carrier so the numbers stay comparable. Most insurers offer online quote tools that take 10 to 15 minutes, and obtaining three to five quotes takes less than an hour total. The difference between your highest and lowest quote often exceeds 35 percent, which means shopping around directly impacts your wallet.
Review Your Coverage Every Year
Rates change yearly, new discounts launch, and your home’s value shifts, yet most homeowners never revisit their coverage after purchase. Schedule a review every 12 months and specifically ask your agent about discounts you haven’t claimed yet, because carriers don’t automatically apply savings you don’t request. Washington homeowners often miss earthquake coverage discounts or bundling incentives simply because they never asked whether their current package included them.
If your home’s value increased due to renovations or market appreciation, your coverage limits may no longer match your actual replacement cost. This leaves you underinsured and potentially overpaying for inadequate protection. Request updated quotes from at least two other carriers during your annual review, because the carrier offering the best rate three years ago may no longer be competitive today.
Uncover Hidden Savings Through Direct Questions
The slow creep of overpaying happens to most homeowners over time without active intervention. Your track record as a customer matters significantly more than most people realize-staying claims-free for three to five years typically qualifies you for loyalty discounts ranging from 10 to 20 percent. Different carriers weight past claims differently, so moving your policy to a company that views your history more favorably can produce substantial savings.
This practice of annual reviews and multi-carrier comparisons typically uncovers savings that were sitting on the table waiting to be claimed. Once you’ve identified your best rate, the next step involves understanding which specific mistakes to avoid so your coverage actually protects you when you need it most.
Common Mistakes Kirkland Homeowners Make When Shopping for Insurance
Underestimating Your Home’s Replacement Cost
Most Kirkland homeowners underestimate their home’s replacement cost, and that mistake directly inflates insurance premiums or leaves them dangerously underinsured. The average home in Kirkland costs between 650 and 750 dollars per square foot to rebuild, according to recent construction cost data, yet many homeowners base coverage limits on their original purchase price from years ago. If you bought your home for 400,000 dollars in 2015 but it would cost 550,000 dollars to rebuild today, carrying a 400,000 dollar coverage limit means you’re either overpaying for inadequate protection or facing a massive gap when you file a claim.
Request a professional home valuation specifically for insurance purposes, not just a real estate appraisal. This takes 30 minutes and costs nothing through most carriers. Your agent can also use replacement cost calculators that factor in local construction rates, materials, and labor costs specific to Kirkland. Overestimating your home’s value wastes money on premiums you don’t need, while underestimating creates financial disaster if disaster strikes.
Overlooking Kirkland’s Specific Local Hazards
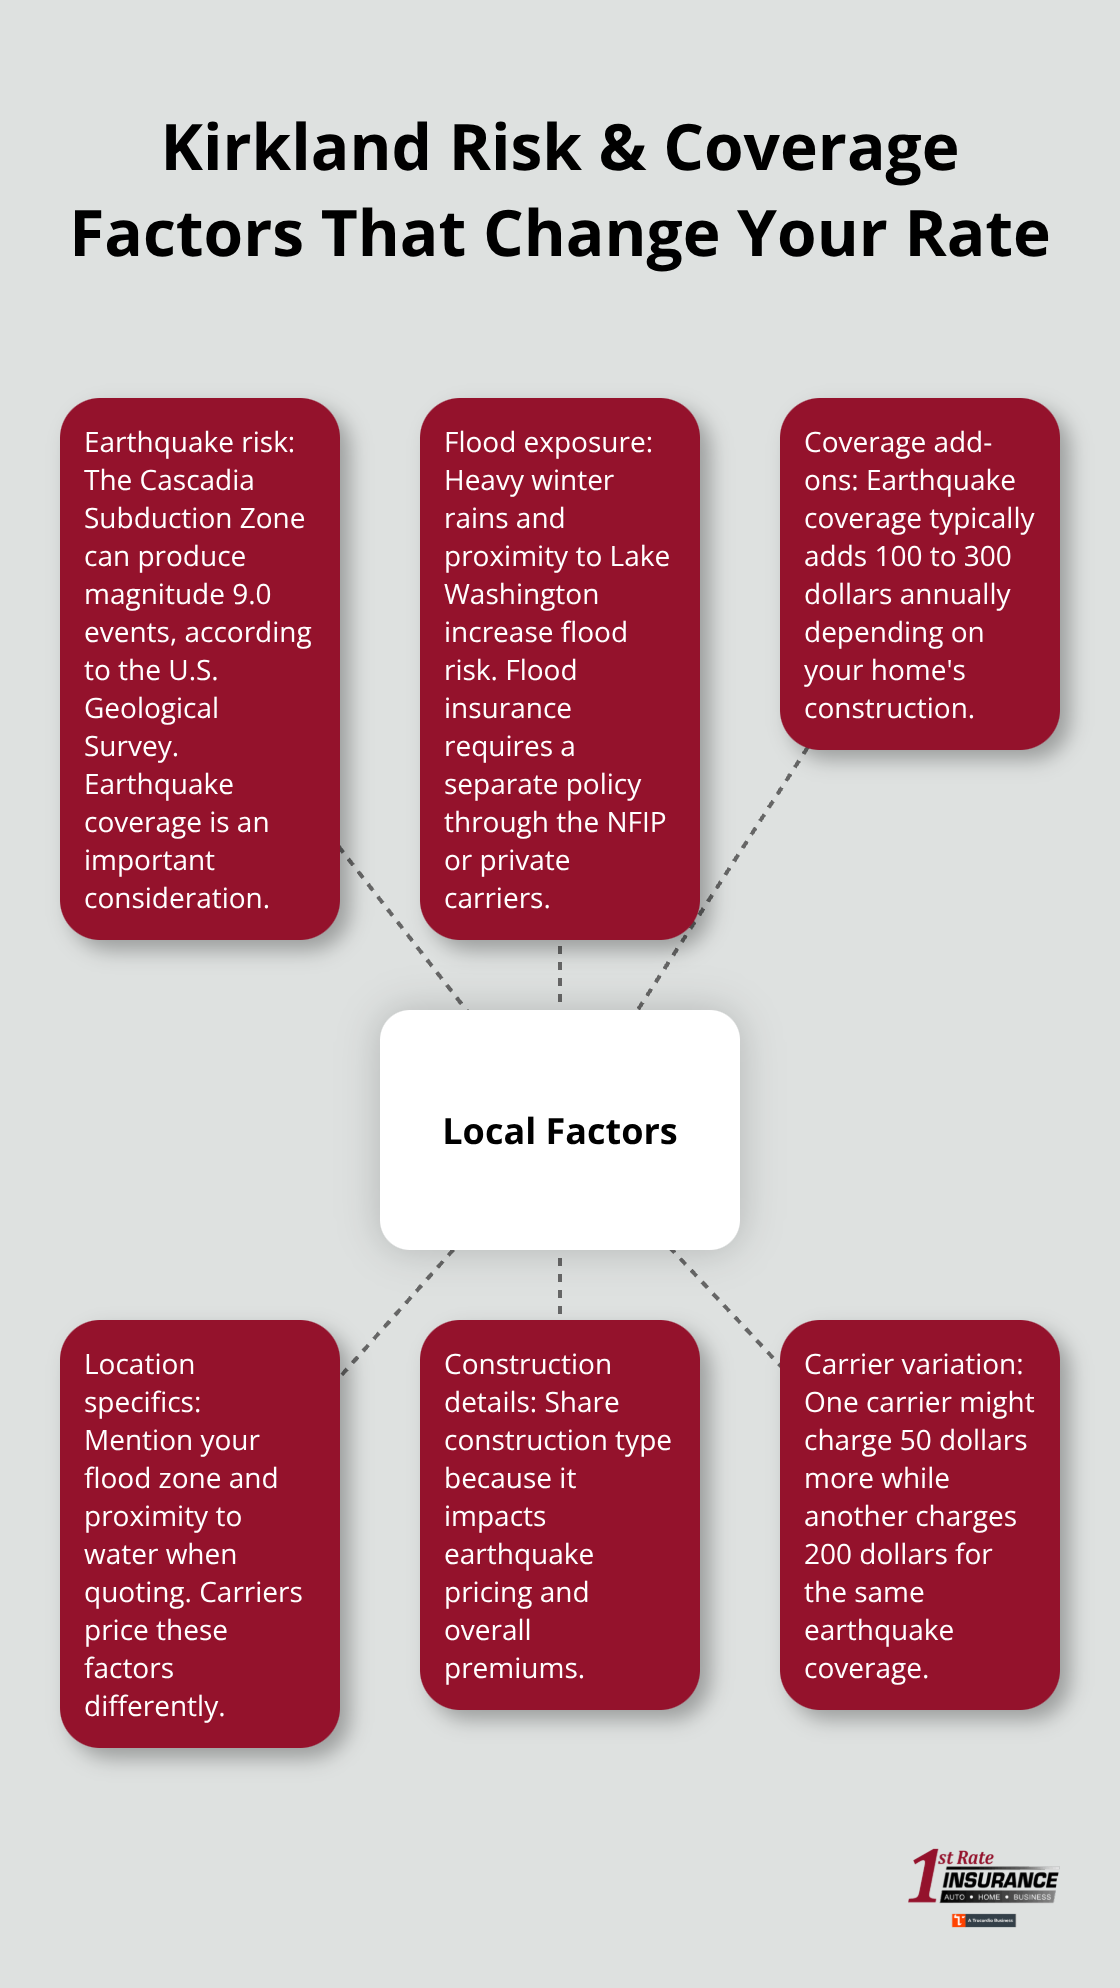
Kirkland’s geography makes it vulnerable to specific hazards that standard homeowners policies either exclude or require separate coverage to address. The Pacific Northwest experiences significant earthquake risk, with the Cascadia Subduction Zone capable of producing magnitude 9.0 events according to the U.S. Geological Survey. Flooding from heavy winter rains and proximity to Lake Washington creates additional exposure that standard policies don’t cover.
Most Kirkland homeowners never ask whether their current policy includes earthquake or flood protection, assuming these catastrophes won’t happen to them. That assumption costs money when you need it most. Flood insurance requires a separate policy through the National Flood Insurance Program or private carriers, and earthquake coverage typically adds 100 to 300 dollars annually depending on your home’s construction. When you obtain quotes, specifically mention your home’s flood zone, proximity to water, and construction type, because carriers price these factors differently. One carrier might charge 50 dollars more for earthquake coverage while another charges 200 dollars for the same protection.
Shopping Without Comparing Multiple Quotes
Accepting the first quote you receive leaves thousands of dollars on the table. The same house with identical coverage costs 40 to 60 percent more at one carrier than another, according to the National Association of Insurance Commissioners. Most Kirkland homeowners stop after requesting two quotes and assume they’ve completed their research, never discovering the variation that exists across carriers.
When you request quotes, provide identical information to each carrier so the numbers stay comparable. Most insurers offer online quote tools that take 10 to 15 minutes, and obtaining three to five quotes takes less than an hour total. The difference between your highest and lowest quote often exceeds 35 percent, which means shopping around directly impacts your wallet. First Rate Insurance Plus, Inc. shops more than 20 carriers, which allows us to match you with companies that offer competitive rates for your specific situation in Kirkland.
Final Thoughts
Finding the best Kirkland homeowners discounts WA requires three concrete actions that most residents skip. First, you need to compare quotes across multiple carriers instead of accepting the first offer. The data shows that identical coverage costs 40 to 60 percent more at one carrier than another, which means your shopping effort directly translates to hundreds of dollars in annual savings.
Second, you must ask specific questions about discounts you don’t automatically receive. Bundling, security features, loyalty rewards, and local hazard coverage all require you to mention them explicitly to your agent. Third, schedule annual reviews to catch rate increases and new discounts before they disappear.
Local knowledge separates homeowners who overpay from those who get genuine value. Kirkland’s earthquake risk, flooding exposure, and construction costs differ from other Washington communities, which means generic quotes from national carriers often miss the mark. Carriers price these local factors differently, so shopping around reveals which companies understand your specific situation best. Visit First Rate Insurance Plus, Inc. to request quotes from multiple carriers at once and find your best rate.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.

