Multi‑Policy Umbrella WA: Simplify Protection Across All Policies
Managing multiple insurance policies across your home, car, and personal liability can feel overwhelming. A multi-policy umbrella in WA combines your coverage into one streamlined protection plan that guards against major financial losses.
We at First Rate Insurance Plus, Inc. help Washington families eliminate the complexity of juggling separate policies while maximizing their liability protection.
How Umbrella Coverage Works With Your Existing Policies
The Layered Protection Structure
An umbrella policy is a secondary liability policy that activates after standard home, auto, or watercraft policy limits are exhausted. Washington residents typically carry home liability limits of $100,000 to $300,000 and auto liability limits of $25,000 to $100,000. A single serious accident exhausts these limits in minutes. When that happens, your umbrella policy takes over, providing an additional $1 to $5 million in coverage. This layered approach costs far less than raising your underlying policy limits to extreme amounts.
Affordability That Makes Sense
A $1 million umbrella policy in Washington averages between $150 and $300 annually, making it one of the most affordable ways to protect substantial assets. Most households find this investment trivial compared to the financial devastation a major liability claim could cause. The protection-to-cost ratio makes umbrella coverage a smart financial decision for homeowners and vehicle owners alike.
Multi-Policy Bundling Advantages
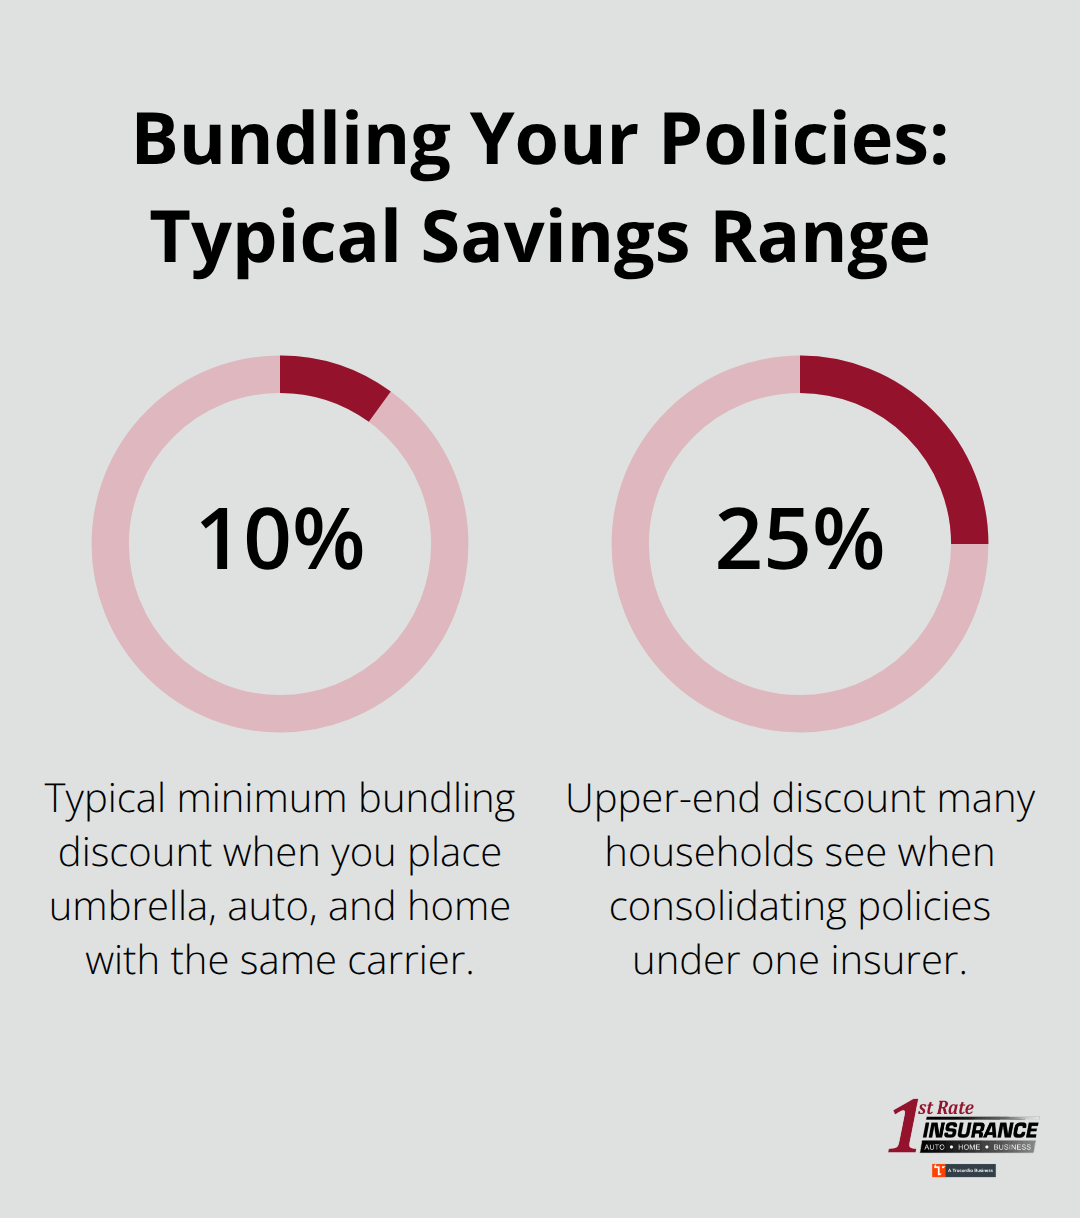
Multi-policy bundling amplifies this advantage significantly. When you combine your umbrella with auto, home, and other policies through the same carrier, insurers typically reduce your overall premium by 10 to 25 percent according to industry data from the National Association of Insurance Commissioners. Beyond price, bundling creates operational efficiency that matters in real situations. You contact one agent instead of juggling multiple carriers when you need coverage questions answered or claims filed.
You receive one renewal notice instead of four separate ones cluttering your inbox.
Simplified Management and Claims
You maintain a single account dashboard tracking all your policies. Washington families with bundled coverage report faster claims resolution and fewer billing errors because one company manages your entire risk profile. This simplification becomes invaluable when you’re actually dealing with an accident, injury, or liability claim rather than managing policies during calm periods. The operational benefits extend beyond convenience-they translate into real savings and peace of mind when you need them most.
What Happens When Claims Arise
Understanding how these layers activate matters when you file a claim. Your home or auto insurer pays first up to their policy limits, then your umbrella coverage activates to cover amounts beyond that threshold. This coordination happens automatically, though having all policies with one carrier (or at least one agent who knows your full coverage picture) prevents gaps and confusion during stressful moments.
What You Actually Save With Multi-Policy Bundling
Discounts That Add Up Fast
Bundling your umbrella policy with home and auto coverage through one carrier generates real financial benefits that extend far beyond a simple discount percentage. Washington families bundling auto, home, and umbrella policies with the same insurer typically receive discounts ranging from 10 to 25 percent. A household paying $1,200 annually for auto coverage and $900 for home insurance could reduce that combined premium by $420 to $1,050 per year by adding an umbrella policy and consolidating carriers. That money stays in your account instead of flowing to multiple insurers. The financial advantage compounds when you factor in operational efficiency. Managing one renewal date, one billing cycle, and one customer service contact eliminates the administrative overhead of juggling separate companies. You spend less time on paperwork and fewer hours tracking policy documents scattered across different carriers.
Claims Resolution Accelerates With One Agent
One agent who understands your complete coverage picture prevents the coordination failures that plague multi-carrier setups. When a liability incident occurs on your property, your home insurer needs to know if your umbrella policy will backstop their coverage. When a vehicle accident creates an injury claim exceeding your auto liability limit, the claims adjuster needs immediate confirmation that your umbrella activates at the correct threshold. Washington families with fragmented coverage across multiple carriers experience delays while separate companies communicate about claim responsibility.
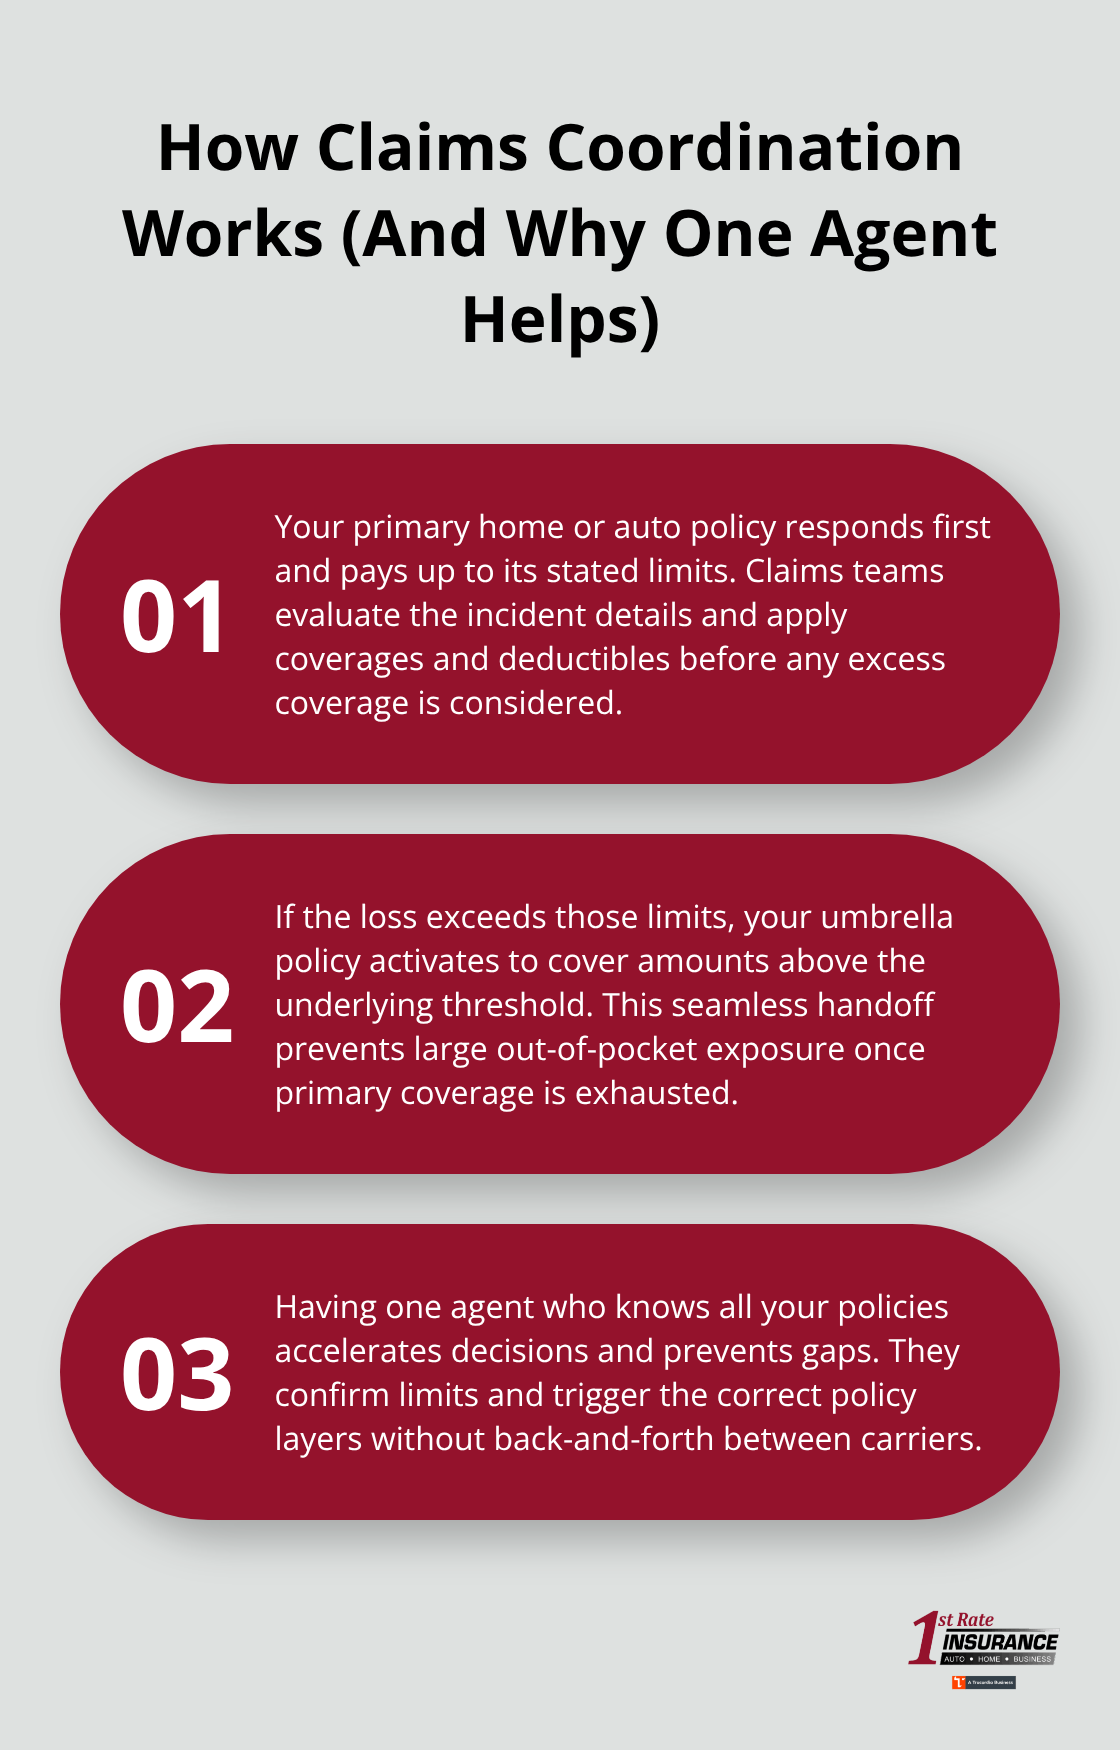
A single agent coordinating your bundled policies eliminates this back-and-forth entirely. That agent knows your exact limits across all policies, your deductibles, and your coverage gaps before you even dial their number. Claims resolution accelerates significantly when one person owns accountability for your entire risk profile rather than three separate companies operating independently.
Protection Matches Your Real Exposure
Umbrella coverage bundled with your existing policies creates liability protection across the areas where Washington families face genuine financial exposure. A serious injury on your property, an at-fault vehicle accident, or a dog bite incident can generate medical bills, legal fees, and damage settlements exceeding your standard home or auto liability limits within hours. Your $300,000 home liability limit disappears quickly when one injury claim involves hospitalization, surgical costs, and ongoing care. Your $100,000 auto liability limit evaporates in a single serious vehicle accident with multiple injured parties. A $1 million umbrella policy activated through multi-policy bundling provides the financial barrier between your assets and catastrophic liability exposure. The protection layers you build through bundling match real-world risk rather than theoretical scenarios-and that alignment matters most when an actual incident tests your coverage.
When Liability Claims Exceed Your Standard Coverage
Property Injuries Drain Coverage Fast
A guest slips on your deck and fractures their hip, suddenly facing $150,000 in surgical and rehabilitation costs. Your home liability policy maxes out at $300,000, which sounds substantial until medical bills, legal fees, and potential settlement costs accumulate. The American Journal of Emergency Medicine reports that a single hospitalization for a serious fall injury averages $35,000 to $75,000 before considering ongoing physical therapy or long-term care needs. Add a lawsuit into that scenario and your standard coverage erodes within weeks. Your umbrella coverage activates exactly when you need it most, providing protection beyond existing limits and coverages of other policies.
Vehicle Accidents Create Instant Financial Exposure
Vehicle accidents generate even faster financial exposure than property injuries. A single at-fault collision involving multiple injured parties can create liability claims exceeding $500,000 when medical expenses, lost wages, and pain-and-suffering damages combine. Washington’s auto liability minimum is only $25,000 per person-a figure that covers almost nothing in serious injury cases. The National Highway Traffic Safety Administration estimates that fatal and serious injury crashes cost society over $242 billion annually, with individual catastrophic claims routinely reaching six figures. Your $100,000 auto liability limit disappears instantly in these situations, which is precisely why umbrella coverage attached to your auto policy provides critical financial protection.
Pet Liability Claims Spike Dramatically
Dog bite claims have increased 90 percent over the past two decades according to the Insurance Information Institute, with average settlement costs now exceeding $44,000 per incident. A serious bite requiring emergency room treatment, plastic surgery, or resulting in permanent scarring creates medical expenses that dwarf your homeowner’s liability limit within days. Your homeowner’s policy typically covers pet liability up to your standard limits, but umbrella coverage extends that protection to $1 million or more. This matters because one aggressive incident can destroy your finances if an injured party pursues legal action.
Why Standard Limits Fall Short
The practical reality facing Washington residents is that standard home and auto liability limits no longer match actual injury claim costs. Medical inflation, litigation expenses, and legitimate damage settlements have outpaced policy limits for years. Home, vehicles, and pets expose you to genuine liability risk every single day. Umbrella coverage transforms that exposure from a potential financial catastrophe into a manageable risk by layering additional protection over your existing policies, creating a comprehensive liability barrier that protects against the specific incidents most likely to create financial devastation.
Final Thoughts
Washington families face genuine liability exposure every single day through their homes, vehicles, and pets. Standard coverage limits no longer match actual injury claim costs, leaving your assets vulnerable to financial devastation when serious incidents occur. A multi-policy umbrella in WA bridges that gap by layering $1 to $5 million in additional protection over your existing policies at a fraction of what you’d pay to raise underlying limits.
Bundling your umbrella with home and auto policies generates tangible savings and operational benefits that matter when incidents actually occur. You receive discounts ranging from 10 to 25 percent on your combined premiums, eliminate the administrative burden of managing multiple carriers, and gain faster claims resolution through one agent who coordinates your complete coverage picture. This coordination prevents the failures that plague fragmented policies across different companies.
We at First Rate Insurance Plus, Inc. help Washington families build comprehensive protection that matches their actual risk exposure. Contact us today for a personalized quote that shows exactly how much you’ll save by consolidating your coverage and adding umbrella protection.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
