Kirkland Rental Property Insurance: Protecting Your Investment With Local Expertise
Rental property owners in Kirkland face distinct insurance challenges that standard homeowners policies simply don’t address. At First Rate Insurance Plus, Inc., we’ve helped countless landlords discover the coverage gaps that leave their investments vulnerable.
The right Kirkland rental property insurance policy protects your building, your income, and your liability exposure. This guide walks you through what you actually need to know.
What Landlords Actually Need to Cover in Kirkland
Washington’s Rental Property Insurance Landscape
Rental property insurance in Washington operates under a completely different set of rules than homeowners coverage, and Kirkland landlords often underestimate how exposed they actually are. Washington State doesn’t legally mandate landlord insurance the way some states do, but your mortgage lender almost certainly will. More importantly, your liability exposure as a landlord is substantially higher than as a homeowner. Washington courts have consistently held property owners responsible for tenant injuries, with verdicts regularly exceeding $500,000 for serious incidents. Standard homeowners policies explicitly exclude rental income and liability protection for tenant-occupied properties, which means you operate without coverage on your most critical exposures.
The Three Coverage Pillars You Need
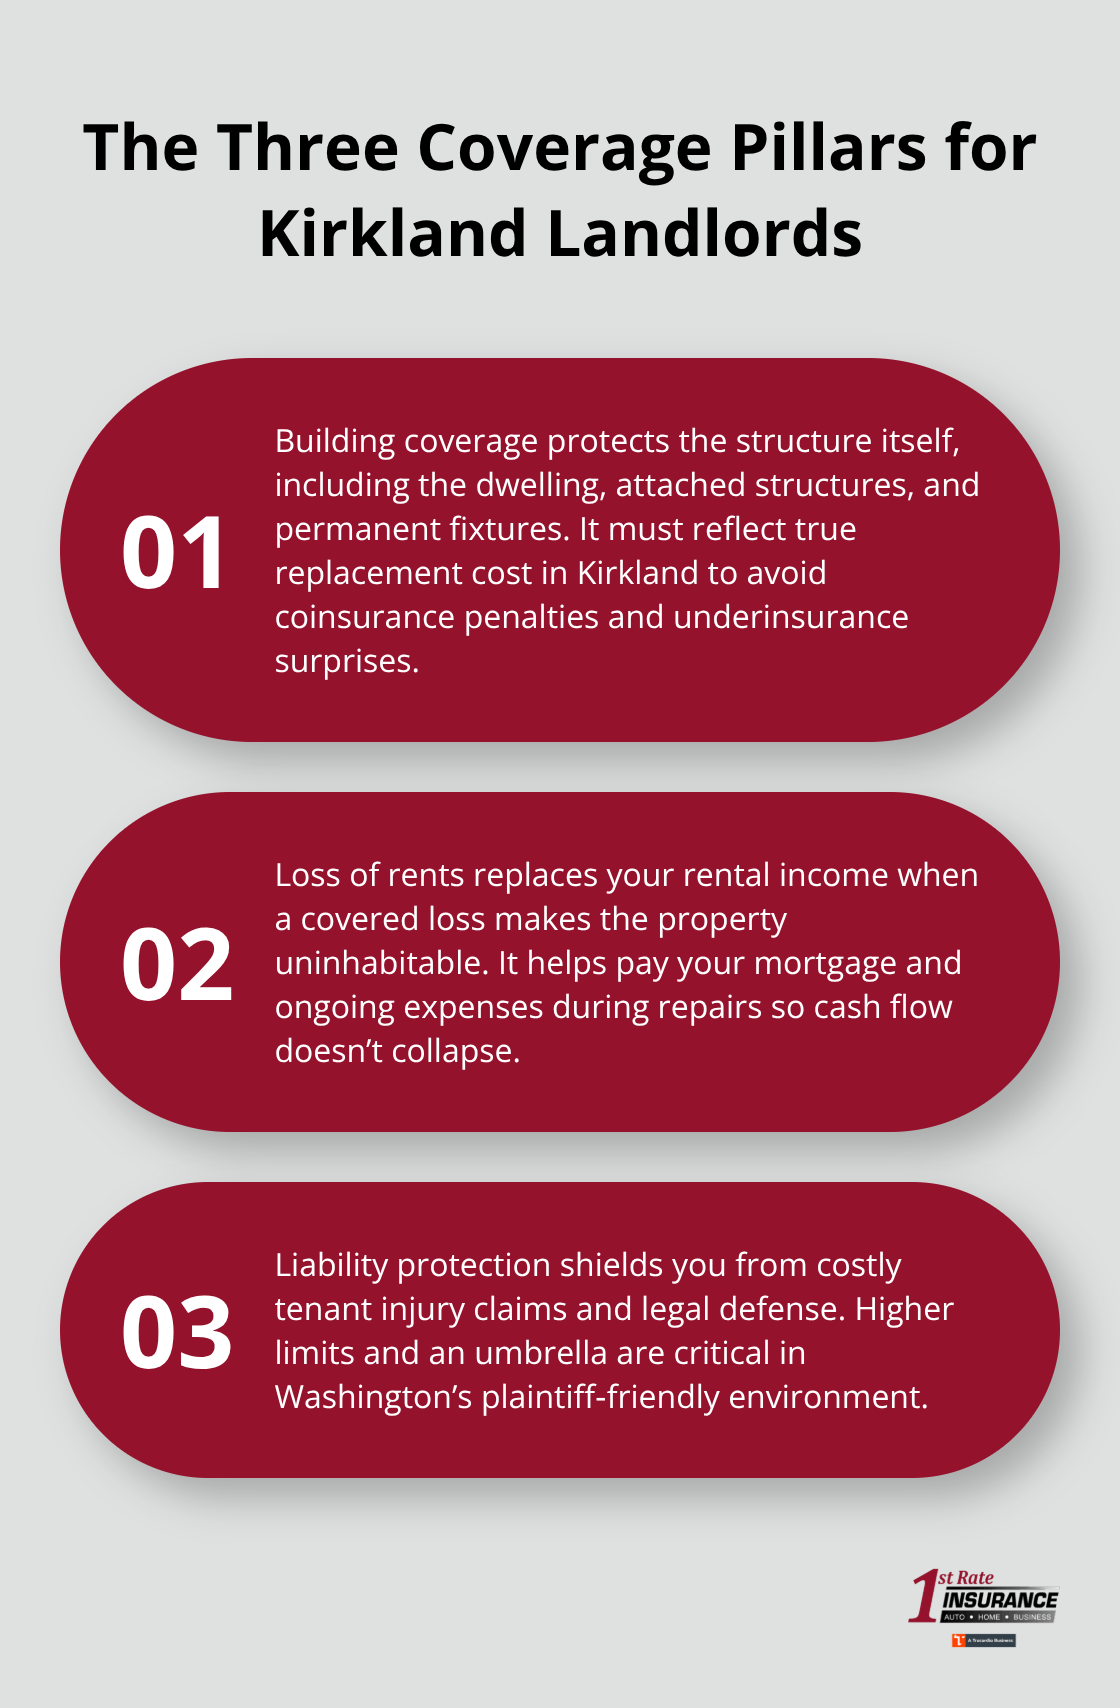
The three coverage pillars you need are building coverage, loss of rents, and liability protection-and they’re not optional if you want to actually protect your investment. Building coverage protects the structure itself, which sounds straightforward but requires specific attention in Kirkland. Your policy needs to cover the dwelling structure, attached structures like garages or sheds, and any permanent fixtures.
Most landlords underinsure their properties by 20 to 30 percent, which triggers coinsurance penalties when you file a claim.
Building Coverage and Loss of Rents
A 2,000 square foot rental property in Kirkland typically needs $300,000 to $400,000 in building coverage minimum. Loss of rents coverage is where many landlords get blindsided-this covers your rental income if the property becomes uninhabitable due to a covered loss. If a fire makes your rental unit unlivable for six months, loss of rents pays your mortgage, property taxes, and ongoing expenses while you earn zero income.
Liability Protection and Additional Coverage
Liability coverage is non-negotiable because tenant injuries are expensive. A tenant slip-and-fall on your property with a broken leg and medical bills can generate claims well over $100,000, and Washington juries tend to be generous. Your policy should include medical payments coverage, which typically covers up to $5,000 in immediate medical expenses without determining fault. Umbrella policies add an additional layer of protection (usually $1 million in coverage), and they cost relatively little at $150 to $300 annually for landlords.
Moving Forward With Your Coverage Strategy
The key is understanding that you need all three components working together, not picking and choosing based on budget. Local insurance agents who understand Kirkland’s specific risks can help you structure these coverages correctly and identify which carriers offer the best rates for your situation.
Why Local Agents Outperform National Platforms
Kirkland’s Unique Risk Profile Demands Local Knowledge
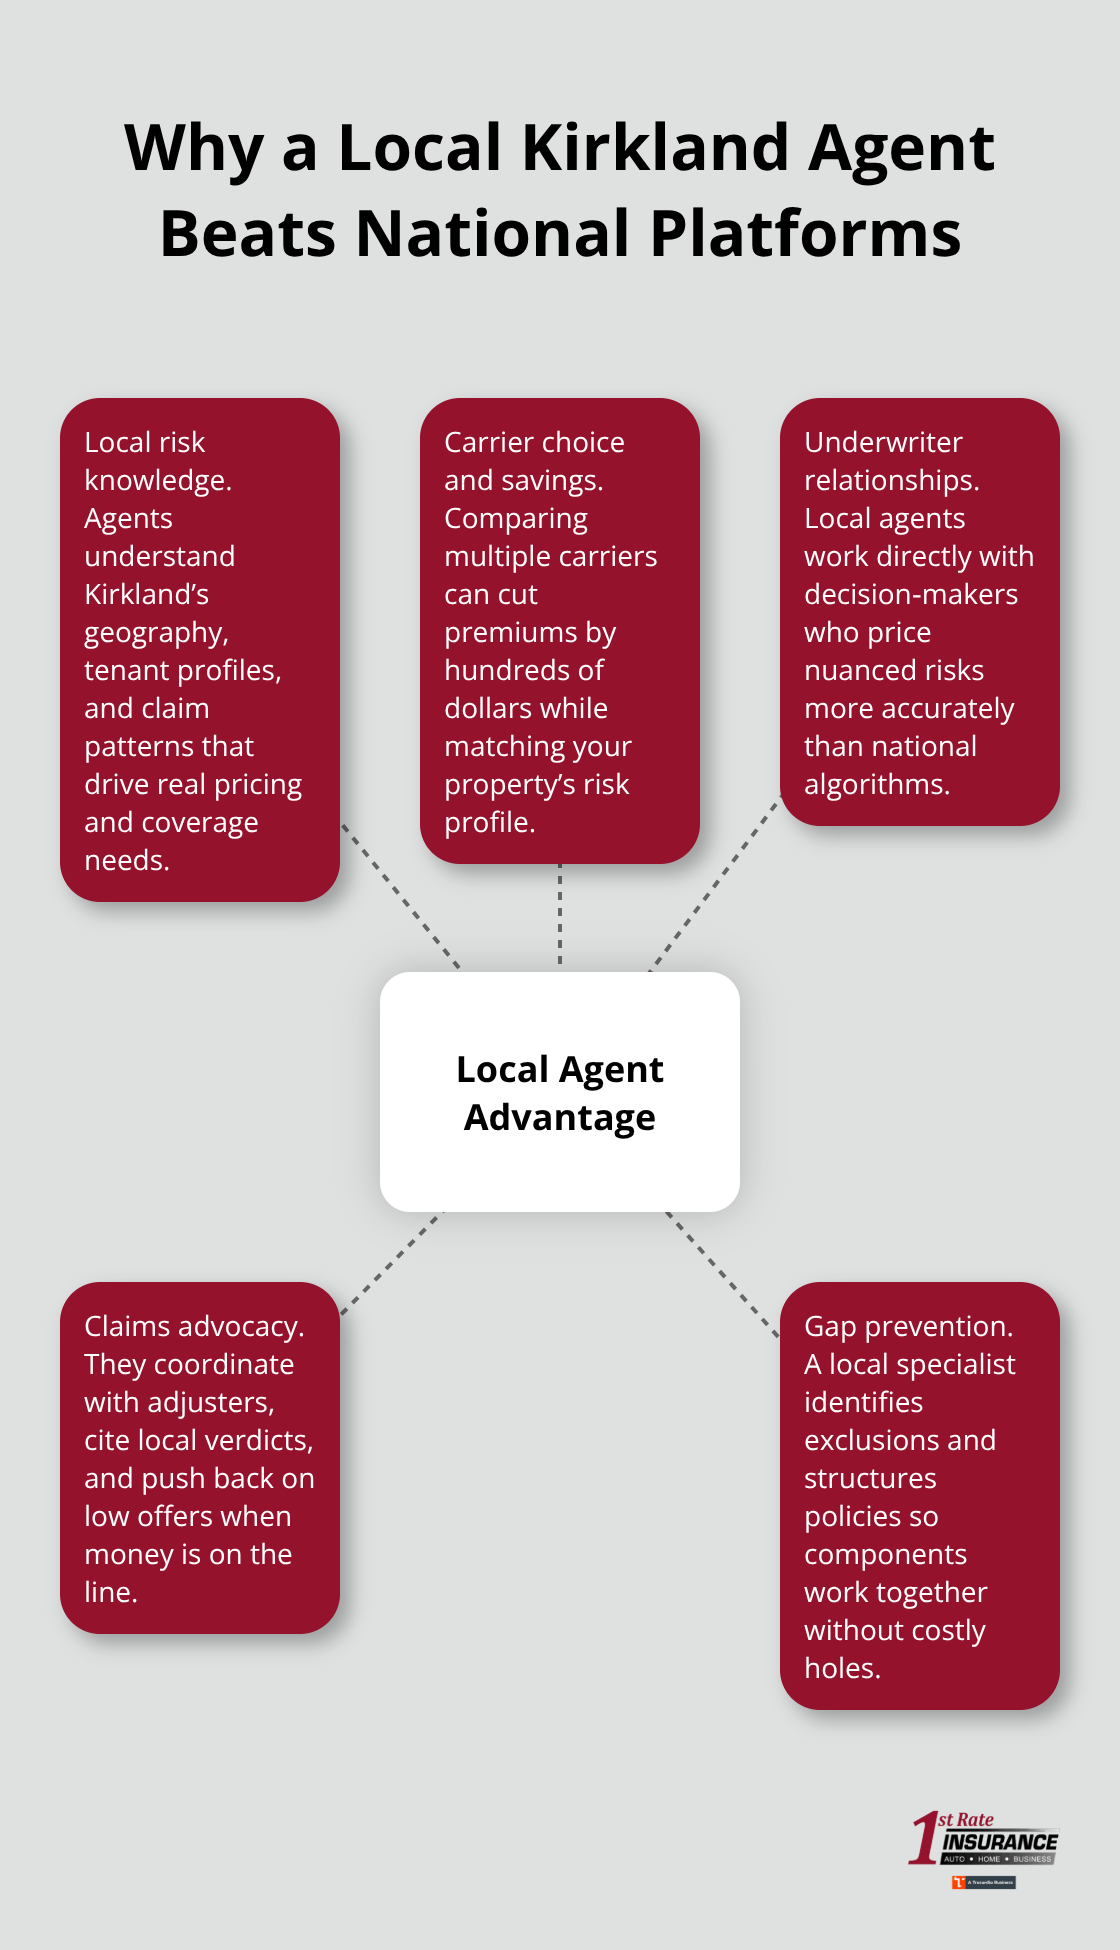
Kirkland landlords who shop for rental property insurance online or through national carriers typically make one critical mistake: they treat rental coverage like homeowners insurance, which it absolutely isn’t. A local agent who specializes in landlord policies understands that Kirkland’s specific geography, tenant demographics, and local claim patterns shape what coverage actually matters. Properties near the Deschutes River face different flood risks than homes on elevated terrain, and agents familiar with the area know which carriers price accordingly. National online platforms charge flat rates across Washington State and rarely adjust for local factors, which means you either overpay or leave gaps in coverage. A local agent identifies these gaps before you file a claim and learns they don’t apply.
Access to Multiple Carriers Cuts Your Premiums
Access to multiple carriers directly translates to lower premiums for landlords willing to move beyond the first quote they receive. Kirkland rental property owners who compare quotes across just three carriers typically save between $400 and $800 annually on their landlord policies, according to data from the National Association of Insurance Commissioners. First Rate Insurance Plus, Inc. shops more than 20 carriers specifically to find rates that reflect your property’s actual risk profile, not some national algorithm that treats Kirkland the same as rural Montana. When you work with a local agent, you tap into relationships with underwriters who understand your market and price your risk accurately.
Claims Support That Actually Advocates for You
When you file a claim, a local agent advocates directly with the carrier instead of navigating a phone tree where nobody knows your property or your situation. If a tenant injury claim lands on your desk, your local agent coordinates with the carrier, explains Kirkland’s specific liability environment to the adjuster, and pushes back on low settlement offers using comparable verdicts from King County courts. National insurers process claims like assembly line items; local agents treat them like the serious financial threats they actually are. This difference matters most when money is on the line and you need someone in your corner who understands both the insurance and the community.
What Coverage Options Actually Look Like for Your Property
The next step involves understanding which specific coverage options work best for your rental situation in Kirkland, and how to structure them so they work together instead of leaving expensive gaps.
Key Coverage Options for Kirkland Rental Investors
Building Coverage That Matches Your Property’s Real Value
Building coverage for Kirkland rentals demands precision because underinsurance triggers coinsurance penalties that wipe out your claim recovery. A 2,000 square foot rental in Kirkland typically requires building coverage based on replacement cost per square foot, which in Washington ranges from $200 to $350 according to current construction data. You need to cover the dwelling structure, detached garages, sheds, and permanent fixtures like built-in appliances and flooring. Most landlords underinsure their properties by 20 to 30 percent, which means coinsurance penalties reduce your claim payout significantly when damage occurs.
Loss of Rents: The Coverage Landlords Ignore Until They Need It
Loss of rents coverage protects your rental income if the property becomes uninhabitable after a covered loss. If a kitchen fire makes your rental unlivable for eight months while you rebuild, loss of rents pays your mortgage, property taxes, insurance premiums, and utilities while your income sits at zero. Most carriers recommend loss of rents coverage equal to 12 months of rental income, which protects you during the reconstruction period plus the time it takes to find and screen new tenants. Without this coverage, you absorb all expenses while earning nothing-a financial disaster that forces many landlords to sell.
Liability Protection: Your Defense Against Expensive Tenant Injury Claims
Liability protection in Kirkland demands aggressive coverage limits because Washington courts award substantial damages in tenant injury cases. A tenant slip-and-fall with a broken leg and surgery typically generates medical bills exceeding $50,000, and King County juries regularly award additional damages for pain and suffering that push total verdicts above $200,000. Your standard landlord policy includes $300,000 in liability coverage, but this barely covers a serious injury case with legal defense costs included. An umbrella policy adds $1 million in additional liability coverage for $150 to $300 annually, which protects you against a verdict that could force you to sell the property.
Earthquake and Flood Coverage: Specialized Protection for Puget Sound Risks
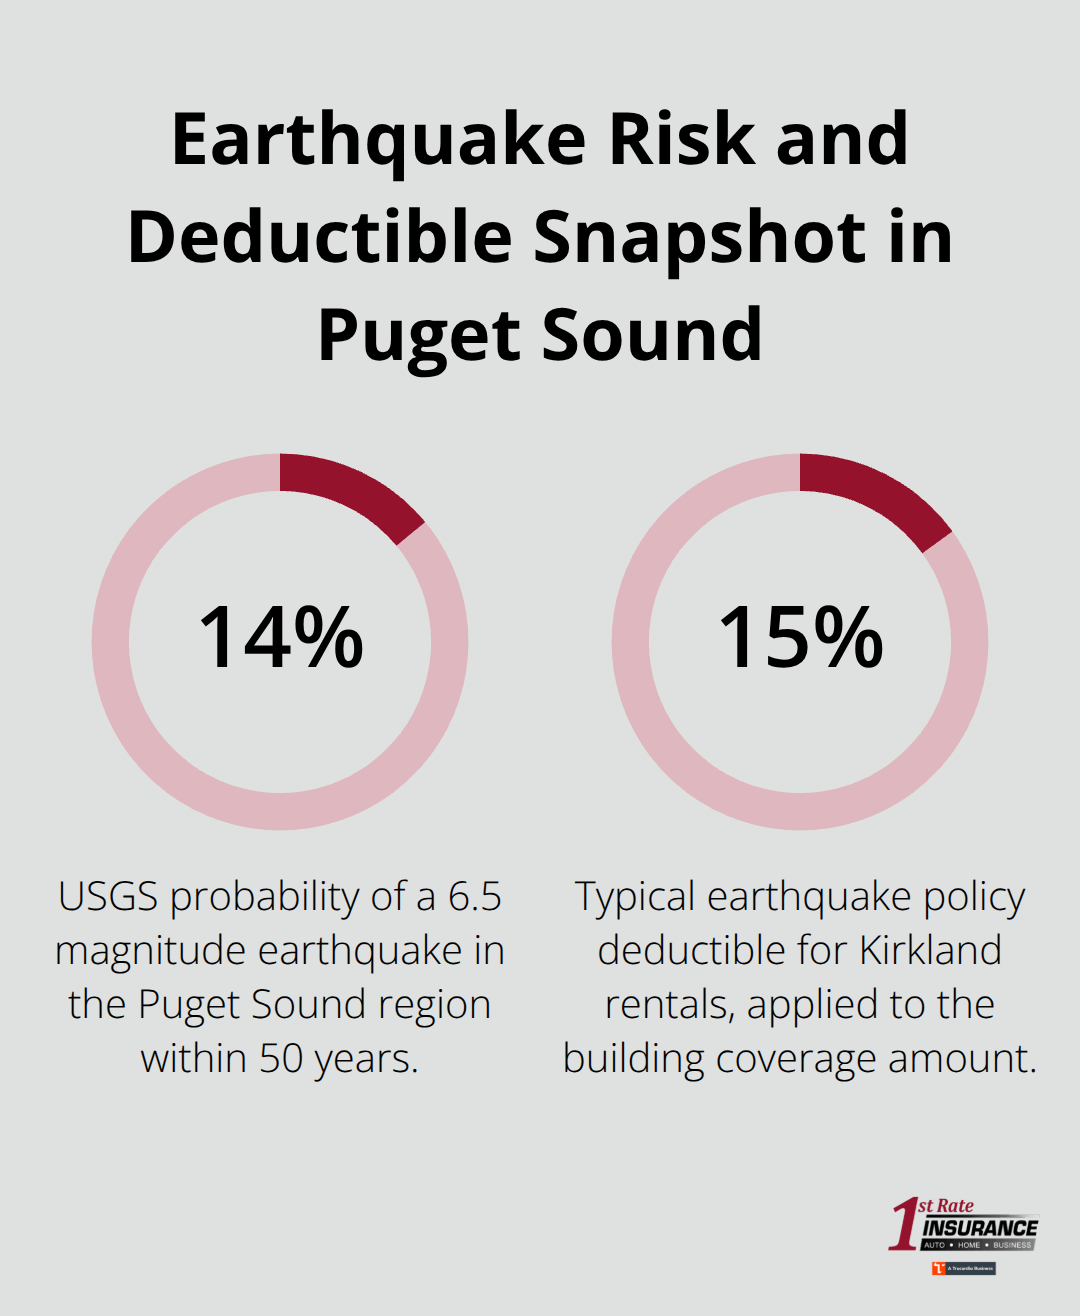
Natural disaster coverage in Washington requires separate policies because standard rental policies exclude earthquake and flood damage, yet Kirkland faces both risks. The Puget Sound region sits in a moderate earthquake zone, and the U.S. Geological Survey estimates a 14 percent probability of a 6.5 magnitude earthquake in the Puget Sound region within the next 50 years. Earthquake coverage costs $300 to $600 annually for a $350,000 building value in Kirkland and typically carries a 15 percent deductible (meaning you absorb the first $52,500 in damage before coverage kicks in).
Flood insurance operates through the National Flood Insurance Program and applies only if your property sits in a designated flood zone, but Kirkland properties near the Deschutes River or in low-lying areas absolutely need it. NFIP flood policies cost $400 to $1,200 annually depending on your flood zone designation, and they cover building damage plus contents if you add that rider. Standard rental policies cover sudden water intrusion from storms but exclude standing water from flooding. A serious flood event generates $100,000 to $300,000 in damage to a rental property, and without specific flood coverage, you absorb the entire loss while still owing your mortgage. First Rate Insurance Plus, Inc. shops carriers that offer these specialized coverages and layers them with your base rental policy so you understand exactly what’s covered and what sits exposed.
Final Thoughts
Your Kirkland rental property insurance strategy determines whether a single claim bankrupts you or your coverage protects you completely. The three-pillar approach-building coverage, loss of rents, and liability protection-protects your investment against the financial disasters that destroy unprepared landlords. Most landlords identify gaps in their coverage only after filing a claim, which leaves them exposed to losses that standard policies explicitly exclude.
Local agents who understand Kirkland’s specific geography, tenant demographics, and claim patterns identify coverage gaps before they cost you money and shop multiple carriers to find rates that reflect your property’s actual exposure. National online platforms charge flat rates across Washington and miss the local factors that determine your real risk, while a local agent structures your Kirkland rental property insurance policy so all components work together instead of leaving expensive gaps. We at First Rate Insurance Plus, Inc. work with more than 20 carriers to build policies that actually protect your property, your income, and your liability exposure.
Contact us to review your current coverage and identify where your policy falls short against Kirkland’s specific risks.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.

