Redmond Umbrella Policy Benefits: Why You Need Extra Liability Coverage
Your homeowner’s and auto insurance policies have limits. When a serious accident happens, those limits can vanish in seconds.
At First Rate Insurance Plus, Inc., we see Redmond residents face this gap every year. A single lawsuit can cost far more than your standard coverage provides. That’s where Redmond umbrella policy benefits come in-they fill the gap and protect your assets when the unexpected strikes.
How Much Are You Actually Protected?
Standard homeowner’s and auto policies come with liability limits that sound adequate until you need them. Most homeowners carry $300,000 in liability coverage, while typical auto policies max out at $250,000 to $500,000 per incident. These numbers look reasonable on paper, but they crumble fast when serious accidents happen.
A single medical emergency on your property or a multi-car collision can generate bills exceeding $1 million in seconds. Hospital stays, surgical procedures, and ongoing rehabilitation costs have skyrocketed in recent years. According to the Council of Economic Advisers, a serious accident requiring hospitalization and long-term care reaches $2 million or more when you factor in emergency room visits, imaging, surgery, and months of recovery. Your standard coverage simply won’t stretch that far.
Legal Defense Costs Drain Your Wallet Fast
Here’s what most Redmond residents don’t realize: legal fees start accumulating before any settlement happens. A personal injury lawsuit involving serious bodily harm costs $15,000 to $100,000 just in attorney fees and court expenses, according to data from the American Bar Association. Your standard homeowner’s or auto policy covers legal defense up to your liability limit, but once that limit gets exhausted, you pay out of pocket for every additional dollar.
A defendant’s attorney charges $200 to $500 per hour in Washington state, and complex liability cases stretch across months or years. If a jury awards damages beyond your policy limits, you become personally liable for the difference. Wage garnishment and asset seizure become real possibilities. An umbrella policy picks up these legal costs and additional damages, protecting your paycheck and savings account from court judgments that exceed your underlying coverage.
Property Damage Claims Multiply Your Exposure
Property damage liability isn’t just about replacing a fence or fixing a car. When someone gets injured on your property, the damages include medical costs, lost wages, pain and suffering, and sometimes permanent disability compensation. A serious injury at a backyard gathering or on your driveway triggers claims ranging from $500,000 to several million dollars, especially if the injured person faces lifelong care needs.
Multiple injured parties multiply your exposure exponentially. A car accident where you’re at fault and three vehicles are involved means three separate injury claims plus vehicle damage claims. Your $300,000 homeowner’s liability limit or $500,000 auto limit evaporates instantly. The gap between what your standard liability coverage limits cover and what you owe becomes your personal financial responsibility-and that’s exactly where umbrella coverage steps in to protect what you’ve worked hard to build.
How Umbrella Coverage Fills Your Protection Gaps
An umbrella policy operates as a second layer of liability protection that activates only after your home and auto insurance limits are exhausted. When someone sues you for damages exceeding your standard coverage, your umbrella policy picks up where your homeowner’s or auto policy stops, covering the remainder up to your umbrella limit. Most umbrella policies in Washington start at $1 million in additional coverage, though limits of $2 million or $5 million are common for Redmond residents with significant assets. The policy covers bodily injury claims, property damage liability, and legal defense costs that your underlying policies won’t pay.
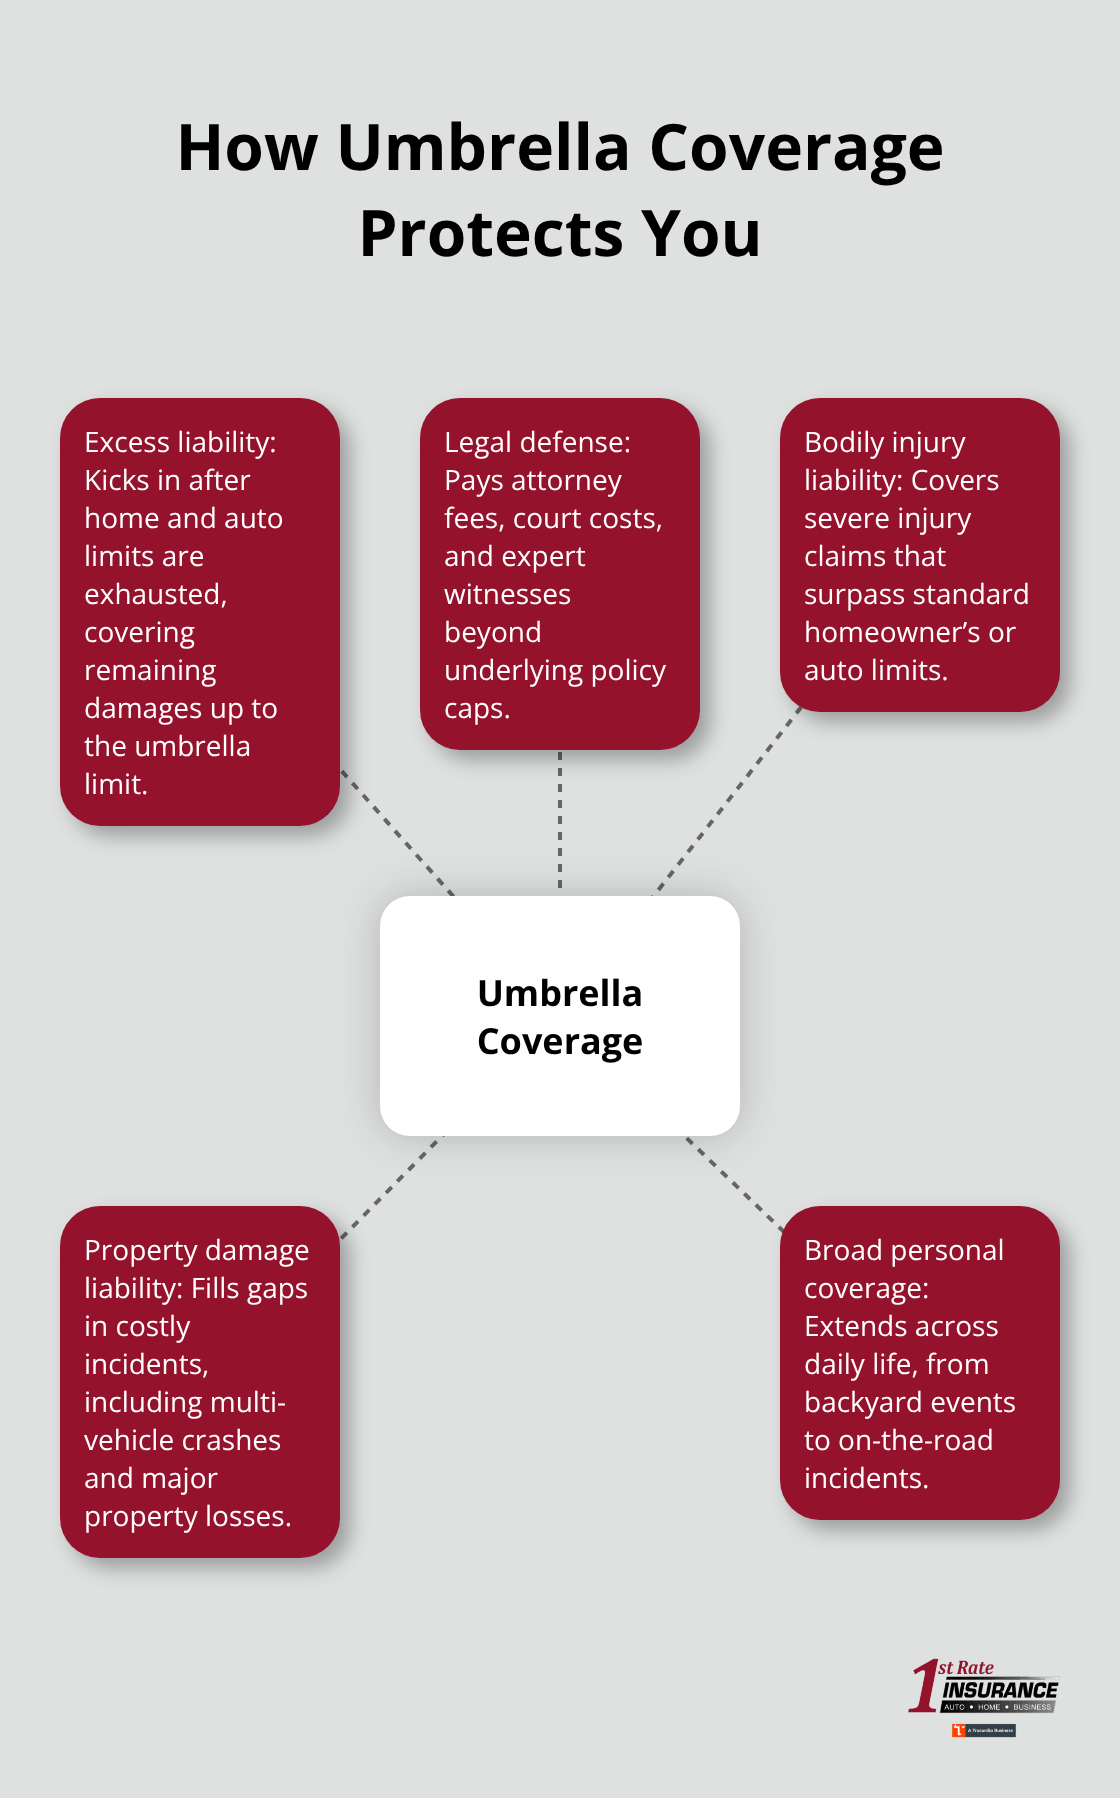
Unlike your home and auto policies, an umbrella policy extends your existing liability protection across all areas of your personal life, from hosting a backyard event to involvement in a multi-vehicle accident.
What Your Umbrella Policy Actually Covers
Your umbrella policy covers the full spectrum of liability exposure that standard policies leave exposed. If someone suffers a serious injury on your property and the medical bills reach $1.5 million, your homeowner’s $300,000 liability limit pays the first $300,000, and your $1 million umbrella policy covers the remaining $1.2 million. Legal defense costs mount rapidly in serious injury cases, and your umbrella policy covers attorney fees, court costs, and expert witness fees that exceed your underlying coverage. Property damage claims follow the same structure-if you cause an accident involving multiple vehicles and the total damages reach $800,000, your auto policy’s $500,000 limit covers the first portion, and your umbrella fills the gap. The umbrella policy also covers liability claims that fall outside typical home and auto scenarios, such as injuries someone sustains while using your swimming pool, trampoline, or recreational equipment on your property.
Determining the Right Coverage Limit for Your Situation
The right umbrella limit depends on your net worth and liability exposure. Financial advisors recommend carrying umbrella coverage equal to at least your total assets, and Fidelity suggests $1 million as a minimum for homeowners with substantial property or frequent social gatherings. If you host regular events, have a pool, own a rental property, or drive frequently, your exposure increases significantly.
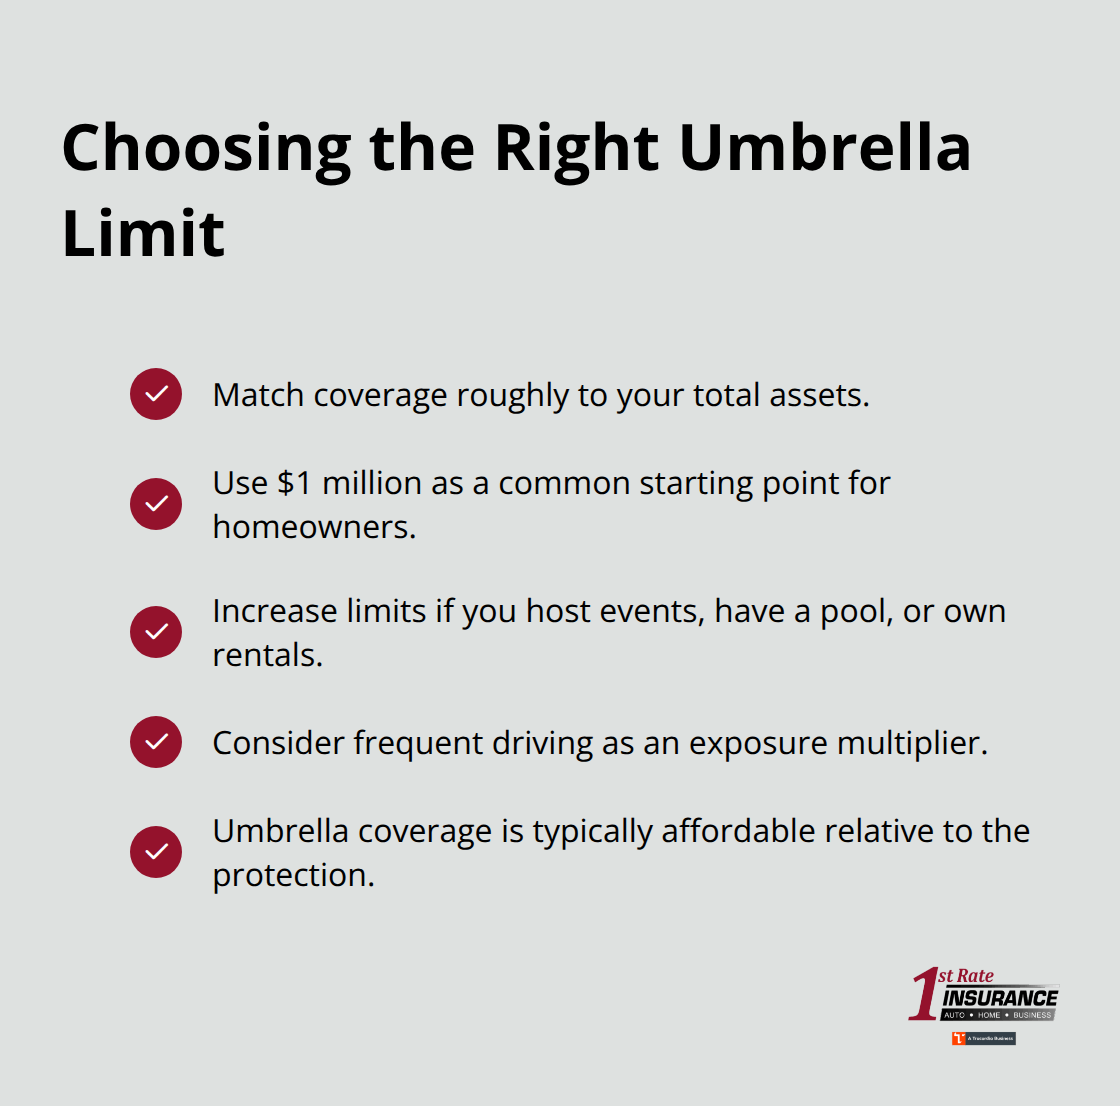
A $1 million umbrella policy typically costs $150 to $300 annually in Washington, making it one of the most affordable insurance purchases you can make relative to the protection it provides.
Finding the Right Umbrella Policy for Redmond Residents
Your specific situation determines what coverage makes sense. First Rate Insurance Plus, Inc., our Kirkland-based agency, shops more than 20 carriers to find umbrella policies that match your needs and budget rather than applying a one-size-fits-all approach. Our licensed agents work with you to assess your liability exposure and recommend appropriate limits based on your circumstances, assets, and lifestyle. The next step involves understanding which real-world scenarios put Redmond residents at greatest risk and how umbrella coverage protects you when these situations occur.
Real-World Scenarios Where Umbrella Coverage Protects Redmond Residents
Serious Injuries on Your Property
A backyard gathering turns tragic when a guest slips on wet pavement and suffers a spinal cord injury requiring permanent care. The medical bills alone reach $2.3 million over the injured person’s lifetime, according to data from the National Spinal Cord Injury Statistical Center. Your $300,000 homeowner’s liability limit evaporates in the first month of hospitalization.
The remaining $2 million becomes your personal debt, and the injured party’s attorney files a judgment against your home and savings account.
Property-related injuries create significant liability exposure for homeowners because they occur on your premises where you hold legal responsibility for visitor safety. A serious fall, drowning in your pool, or trampoline injury involving a child generates liability claims that easily exceed $1 million when permanent disability results. Courts award substantial damages for pain and suffering, lost earning capacity, and future medical care. Your homeowner’s policy stops paying once its limit hits, leaving you personally liable for the remainder.
Multi-Vehicle Car Accidents with Multiple Injured Parties
Car accidents involving multiple vehicles and injured parties create equally devastating exposure. When you cause a collision with three other vehicles and five people suffer significant injuries, the combined medical bills and property damage claims routinely exceed $1.5 million. The National Highway Traffic Safety Administration reports that serious injury accidents average over $100,000 in combined medical and vehicle costs per person injured.
Your auto policy’s $500,000 limit covers a fraction of the total damages, and you absorb the gap personally. An umbrella policy covers these scenarios completely once your underlying policies exhaust their limits, protecting your income and assets from judgments that would otherwise devastate your financial life.
Dog Bites and Pet-Related Incidents
Dog bites and pet incidents round out the highest-risk scenarios because they generate both medical liability and property damage claims simultaneously. A dog bite requiring reconstructive surgery, hospitalization, and infection treatment costs $15,000 to $50,000 in immediate medical expenses. The injured party’s permanent scarring and psychological trauma push liability claims to $300,000 or higher.
Insurance Information Institute data shows dog bite liability claims average $44,760 nationally, making pets a serious exposure for homeowners. An umbrella policy covers these incidents completely, protecting your income and assets when your standard homeowner’s coverage reaches its limit.
Final Thoughts
Redmond umbrella policy benefits protect your financial future when standard coverage falls short. A $1 million umbrella policy costs roughly $150 to $300 annually in Washington, yet it shields assets worth hundreds of thousands or millions of dollars from court judgments. That protection comes at a price point most Redmond residents can afford without straining their budgets.
Serious injuries on your property, multi-vehicle accidents, and pet incidents happen to real people in our community every year. When they occur, the gap between your standard coverage limits and actual damages becomes your personal financial responsibility. Standard homeowner’s and auto policies simply don’t provide enough protection anymore, which is why umbrella coverage matters so much.
Contact First Rate Insurance Plus, Inc. to discuss your umbrella coverage options and identify your protection gaps. Our Kirkland-based team serves individuals and families across Washington with personalized service, and we’ll review your current policies to recommend appropriate umbrella limits based on your assets and lifestyle. Your financial security deserves more than generic recommendations.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
